Hạch toán thuế TNDN (TK 821) là quá trình kế toán ghi nhận, phản ánh số thuế thu nhập doanh nghiệp phải nộp, đã nộp hoặc còn phải nộp trong kỳ để xác định chính xác lợi nhuận sau thuế. Nghiệp vụ này chủ yếu sử dụng TK 8211 (chi phí thuế TNDN hiện hành) qua bút toán ghi nhận Nợ TK 8211 / Có TK 3334 và kết chuyển cuối kỳ sang TK 911. Doanh nghiệp thực hiện tạm nộp hàng quý và quyết toán điều chỉnh chênh lệch vào cuối năm theo các quy định hiện hành (như Luật Thuế TNDN số 67/2025/QH15 áp dụng thuế suất phân theo doanh thu)
Enterprises often encounter difficulties when determining the expenses is subtracted, how to account properly or time recorded matches. Flaws in stitching accounting can lead to arrears of tax, penalty for late payment, or falsify financial statements.
This article Lac Viet will help you master the concepts and methods of accounting to corporate INCOME tax in the correct accounting standards, the current from that help businesses control costs, the optimal tax obligations, limiting financial risk.
1. Accounting for corporate INCOME tax rate is what?
1.1. CIT is what?
Corporate income tax (CIT) is the direct taxes levied on the taxable income of the business news of the profits after deducting reasonable expenses, duly prescribed. This is one of the sources of The state budget is important, at the same time demonstrating social responsibility of business towards the community.
Follow Nghị định 320/2025/NĐ-CP and Thông tư 20/2026/TT-BTC, mức thuế suất phổ biến hiện nay là 20% trên thu nhập chịu thuế. Một số trường hợp được áp dụng mức thuế ưu đãi 10% hoặc 17% nếu hoạt động trong lĩnh vực ưu đãi đầu tư như giáo dục, y tế, nông nghiệp công nghệ cao.
A business must declare temporary pay tax quarterly, based on the profit arises, then redefine the tax payable year-end as reported financial official. Mastering this mechanism helps accountants actively managed funds, avoid filing status lack or excess tax.
1.2. Accounting for corporate INCOME tax rate is what?
Accounting for expenses corporate INCOME tax is the process of accounting record and reflect the amount of corporate income tax payable, paid or was payable during an accounting period. The goal of this work is to determine the exact profit after tax, assurance, financial statements showing the correct results in real business of business.
Specific accounting INCOME tax generally include three main professional:
- Accounting for expenses current tax practice (TK 8211): reflects the tax incurred in the tax period.
- Accounting and pay tax (TK 3334): recognition of obligations, the money the business has to submit to the tax authority.
- Accounting for deferred INCOME tax (if any – TK 347): apply to the account temporary differences between accounting profits and taxable profits.
For example, company A's profit before tax in the year 2024 is 1 billion, the cost is deducted reasonable is 900 million, the remaining $ 100 million is taxable income. INCOME tax payable is 20% × $ 100 million = 20 million. Accounting will record:
- Debt TK 8211 – Costs corporate INCOME tax: 20 million
- Have TK 3334 – CIT must submit: 20 million
Thus, the accounting of the cost of corporate INCOME tax is not only professional recording window, which also helps managers understand the financial situation after tax, performance evaluation, business planning, financial strategy for the next period.
1.3. Thuế suất thuế TNDN theo quy định mới nhất (Luật số 67/2025/QH15)
Từ 01/10/2025, Luật Thuế TNDN số 67/2025/QH15 lần đầu tiên áp dụng cơ chế thuế suất lũy tiến theo doanh thu thay vì mức 20% đồng nhất cho mọi doanh nghiệp như trước đây:
| Nhóm doanh nghiệp | Thuế suất |
|---|---|
| Doanh thu năm ≤ 3 tỷ đồng | 15% |
| Doanh thu năm từ 3 đến 50 tỷ đồng | 17% |
| Doanh nghiệp còn lại (doanh thu > 50 tỷ đồng, không thuộc diện ưu đãi khác) | 20% (mức chuẩn) |
| Lĩnh vực thăm dò/khai thác dầu khí | 25%–50% (Thủ tướng Chính phủ quyết định cụ thể theo từng dự án) |
| Lĩnh vực khai thác tài nguyên quý hiếm | 50% (hoặc 40% tại địa bàn đặc biệt khó khăn, ≥70% hoạt động tại địa bàn đó) |
Chính sách thuế suất theo doanh thu này nhằm hỗ trợ doanh nghiệp nhỏ và vừa.
2. Legal bases and applicable accounting CIT
2.1. Legal grounds made accounting
Accounting for INCOME tax is made based on the text important legal follows:
- Circular 99/2025/TT-BTC từ 01/01/2026 – TK 821/8211/8212/3334/347 giữ nguyên số hiệu: Hướng dẫn chế độ kế toán doanh nghiệp, quy định cách ghi nhận, hạch toán chi phí thuế TNDN hiện hành và hoãn lại.
- Decree 21/2018/ND-CP: detailed Rules of Law enforcement CIT guide, how to determine taxable profit, tax capacity, the type of deduction legitimate.
- Luật Thuế thu nhập doanh nghiệp số 67/2025/QH15 (hiệu lực từ 01/10/2025, thay thế Luật Thuế TNDN số 14/2008/QH12 và các văn bản sửa đổi, bổ sung trước đây) : Xác định phạm vi, đối tượng chịu thuế, nghĩa vụ kê khai, nộp thuế.
- The law on tax Administration no. 38/2019/QH14: detailed Rules of declare and pay tax, handling of violations, arrears, tax refund CIT.
The text is the legal basis for accounting business recorded a tax expense reporting, ensuring compliance with tax obligations.
Applicable objects accounting for corporate income tax:
- Domestic business: includes corporation, company, LIMITED private enterprise.
- Foreign business: with or without permanent establishments in Vietnam but have incurred taxable income in Vietnam.
- The organization of administrative careers, cooperative: When there's activity, production, business and incurred taxable income.
Identifying the correct object applied to help businesses avoid omissions obligations tax reporting, accounting accurate.
2.2. Use accounts and accounting principles cost CIT (TK 821)
| Principle | Content |
| Account use |
TK 8211 – Cost CIT current: Recorded INCOME tax payable based on the results of production and business each quarter or the year. TK 8212 – Cost deferred INCOME tax: Recorded tax arise due to temporary differences between accounting profit and taxable profit according to the accounting Standards in Vietnam. |
| Accounting principles generally |
|
| Principles of Cost accounting INCOME tax-current (TK 8211) |
|
| Principles of Cost accounting deferred INCOME tax (TK 8212) |
|
3. Guide to accounting for INCOME tax new rules need to master to avoid errors for business
In the process of management, business finance, the accounting of corporate income tax (CIT) is one of the important profession that helps reflect the correct tax obligations, ensuring legal compliance, financial reporting accuracy.
Depending on each stage of the year and the business situation, the journal of corporate INCOME tax will be different. The next section will present in detail the business, popular, including: CIT interim quarterly corporate INCOME tax payable year-end, tax arrears, slow money and pay tax, with instructions on how accounting, for example particular illustration.

3.1. Accounting CIT interim quarterly
CIT interim quarterly is the corporate tax payable based on the business results in advance of each quarter. The temporary filing help tax authorities maintain a source of constant, while businesses can allocate tax costs are in year, avoid financial pressure at the end of the year. This is also facility to adjust the taxes upon finalization end of the year.
Meaning of accounting:
- Recorded the tax costs incurred in each quarter on bookkeeping, reflect obligations to The state.
- Support business planning, cash flow, make sure you have enough budget to pay the tax due date.
- Is grounds for comparison with CIT fact when settlement last year, avoid arrears or overpaid.
- Increase transparency compliance help businesses limit legal risks.
How to account:
- Debt TK 8211 – Cost CIT quarter
- Have TK 3334 – INCOME Tax payable
Illustrative example: suppose business ABC has profit before tax, quarter 1 is 500 million, the tax rate CIT rate applicable is 20%:
- CIT advance = 500 million × 20% = 100 million
Lưu ý: mức thuế suất áp dụng trong ví dụ trên (20%) là mức chuẩn cho doanh nghiệp không thuộc diện thuế suất ưu đãi theo doanh thu. Doanh nghiệp có doanh thu năm ≤ 3 tỷ đồng áp dụng 15%, từ 3-50 tỷ đồng áp dụng 17% theo quy định mới tại mục 1.3.
Accounting accounting:
- Debt 8211: 100.000.000
- There are 3334: 100.000.000
Note about deadlines: circular 80/2021/TT-BTC, must declare and pay corporate INCOME tax advance within 30 days from the date of the end of the quarter. The filing late may arise slow money paid, affect the cost of corporate reputation.
3.2. Accounting INCOME tax payable year-end
Last year, the business needs settlement tax based on the financial reporting practice. This step is important to determine the amount of tax payable or refundable, adjusted difference compared to the advance paid for the year. The accounting right help financial statements reflect the honest results, business tax obligations.
Meaning of accounting income tax payable year-end:
- Ensure businesses pay the right amount of tax according to real profits.
- Help balance tax expense in the financial statements, from which there is accurate information for business decisions.
- Minimize the risk of arrears or overpaid avoid incurring penalty costs, money for late payment.
- Is the basis for comparison with the tax authorities, demonstrate the legitimacy and transparency of the business.
How to account:
| Case | How accounting |
| If CIT roughly smaller than it actually is |
|
| If CIT roughly larger than it actually is |
|
Illustrative examples:
- CIT roughly the year: 400 million
- CIT fact, according to the financial statements: 450 million
- Difference must submit more: 50 million
Adjusting entry:
- Debt 8211: 50.000.000
- There are 3334: 50.000.000
Conversely, if the provisional tax payment is 500 million and actual tax 450 million, adjusting entry:
- Debt 3334: 50.000.000
- There 8211: 50.000.000
3.3. Accounting tax arrears CIT
Accounting arrears of INCOME tax occurs when businesses declaration of false data, reported revenues, expenses invalid or after the tax inspection, detection of tax payable. Here are additional taxes in addition to plans to temporarily pay quarterly or end of the year.
Meaning of accounting:
- Reflect tax obligations incurred in addition to the expected help bookkeeping honest.
- To help businesses proactively manage cash flow to pay additional promptly, to avoid incurring penalties for late payment.
- Is the tool control tax risks, reducing the possibility of errors led to disputes with tax authorities.
How to account:
- Debt TK 8211 – the tax Costs incurred
- Have TK 3334 – corporate INCOME Tax payable (part arrears)
Illustrative examples:
- Business XYZ is the tax inspection findings declaration 20 million revenue quarter 2 leads to a lack of 4 million CIT.
- Accounting accounting:
- Debt 8211: 4.000.000
- There are 3334: 4.000.000
Consequences and precautions:
- Consequences: Slow pay or declare false lead to arrears can arise more fines, late payment, influence, credibility and business cash flow.
- Measures: Using accounting software standardized as LV-DX Accounting to automatically calculate, check data before the declaration. Strict control bills, vouchers, financial statements periodically. Training staff accountant about the tax rules latest updates decrees and circulars related.
3.4. Accounted amount for late payment of corporate INCOME tax
Money for late payment is fines that arise when business and pay tax later than the time limit specified. The money for late payment is calculated according to the Law on tax Administration, in order to encourage business tax filing deadlines.
Meaning of accounting:
- Reflect actual costs incurred due to violation of the obligation to pay tax.
- Help business track control risks related to cash flow and legal obligations.
- Support the assessment of effective tax administration, internal improvement, financial planning, regulatory compliance.
How to account:
- Debt TK 811 – other Expenses (money for late payment)
- Have TK 3339 – fines, late payment of tax
Illustrative examples: Business ABC and pay tax quarterly, 1 delay 15 days, the tax charge for late payment is 5 million.
Accounting accounting:
- Debt 811: 5.000.000
- There 3339: 5.000.000
3.5. Accounting processing errors not critical of years ago
Errors not critical that the accounting errors arising from the previous year, but no greater value to the extent to retroactively adjusted according to accounting standards. When discovered, the business need to process by recording the increase or decrease in the cost of corporate INCOME tax of the current year.
Meaning of accounting:
- Ensure accounting records reflect the honest tax obligations.
- Help business adjust the reasonable cost, to avoid incurring errors in financial reports and payment of corporate INCOME tax.
How to account:
| Case | How accounting |
| Case to submit additional (recorded increase in cost current) |
|
| Case is reduce the number of payable (reduced current cost) |
|
Illustrative examples: Business development is to declare the lack of 10 million tax you 2 years ago. Entry-additional:
- Debt 8211: 10.000.000
- There are 3334: 10.000.000
Conversely, if the declaration is superfluous 5 million:
- Debt 3334: 5.000.000
- There 8211: 5.000.000
3.6. Pen calculate the shipping cost CIT current (TK 8211) end
End of the accounting period, the entire cost of corporate INCOME tax, the current must be switched TK 911 – Define business outcomes, to determine the after-tax profit of accuracy of business.
Meaning of accounting:
- The end of all tax expense was incurred is reflected in the business results, ensuring financial statements honest.
- Help collated with the tax authority, determine tax obligations, end of the period.
How to account:
- Debt TK 911 – defined business results
- Have TK 8211 – Cost CIT current
Illustrative example: the Cost of corporate INCOME tax current year is 400 million. The end of the year
- Debt 911: the 400,000,000
- There 8211: the 400,000,000
3.7. Accounting accounting expense deferred INCOME tax (TK 8212)
Costs deferred INCOME tax arises from temporary differences between accounting profit and taxable profit. The recorded, adjusted tax expense deferred help reflect obligations tax future in the financial statements.
Meaning of accounting:
- Reflect tax obligations implicit or refunded in the states to come.
- Help business plan cash flow and assess the actual profit.
How to account:
| Name the account | How accounting |
| Recorded tax expense deferred |
|
| Reduced tax expense deferred |
|
Illustrative examples: Business determine the tax expense deferred incurred 15 million:
- Debt 8212: 15.000.000
- There are 347: 15.000.000
When tuning up 5 million:
- Debt 347: 5.000.000
- There 8212: 5.000.000
4. Note when performing accounting, income tax expense business
In fact, business accounting, the accounting CIT often encounter some errors like:
- Recorded wrong states accounting: For example, the tax costs of quarter 1 is recorded to the 2nd quarter or end of the year, led to the financial statements do not properly reflect the tax obligation in states.
- Teen vouchers valid invoice: If no invoice or voucher in full, expenses, corporate INCOME tax is not recognized, the business to be recollected when the tax check.
- Do not adjust gap estimates: Business only temporary pay tax quarterly, but does not adjust when the settlement last year, leading to wrong numbers between temporary tax filing and tax practice.
How optimal tax obligations legal:
- Allocate a reasonable cost: Ensure costs incurred are recorded correctly states, the right kind of avoiding recognition or omissions.
- The contingency reserve as specified: For example, enterprises can fund the room CIT to backup the account arrears potential to help balance the budget, reduce cash flow risks.
- Control of documents, periodic reports: collated data, profits, temporary tax filing and tax practice, reporting timely adjustment before submission to the tax authority.
Adopt these measures to help businesses minimize the risk of tax arrears, to ensure transparency, accuracy in financial reporting.
5. Ứng dụng phần mềm kế toán Accnet ERP trong hạch toán chi phí thuế TNDN
In the process of accounting and pay tax, businesses often difficult to calculate profit, adjusted difference, interim management, arrears or late payment. The implementation does not only take time but also potential risks, errors, affect the obligations tax cash flow.
Đây chính là lý do nhiều tổ chức, doanh nghiệp đang tìm kiếm giải pháp phần mềm kế toán thông minh. Accnet ERP giúp tự động tổng hợp số liệu, định khoản các bút toán thuế TNDN chuẩn xác và tạo báo cáo theo quy định, từ đó đảm bảo doanh nghiệp hạch toán chi phí thuế TNDN minh bạch, tuân thủ pháp lý.
Lợi ích khi dùng phần mềm kế toán như Accnet ERP:
- Automatic synthesis of data, profit before tax: System calculate profits each quarter, both year to help reduce the risk of errors when determining the tax base.
- Auto account, create reports on CIT: The pen payment of provisional tax calculation, decision, late payment, arrears or late payment is the account automatically, ready to export a report in the form of tax authorities.
- Reduce errors, saving time for accounting: remove calculations, reducing the risk of accounting sai states, omissions vouchers or non-adjustable gap. Help with accounting staff to focus on control, data analysis instead of entering data manually.
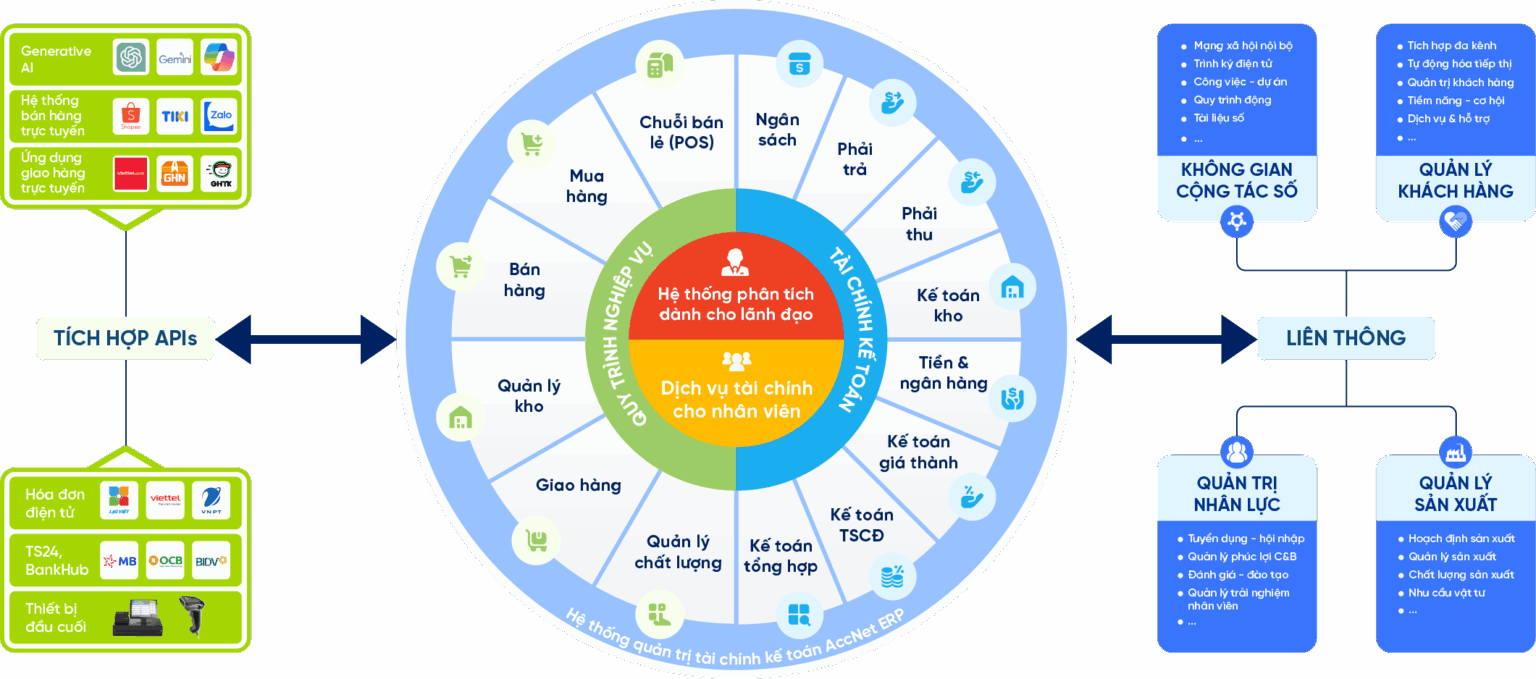
INTEGRATED AI ACCELERATION CONVERTER OF ACCOUNTING
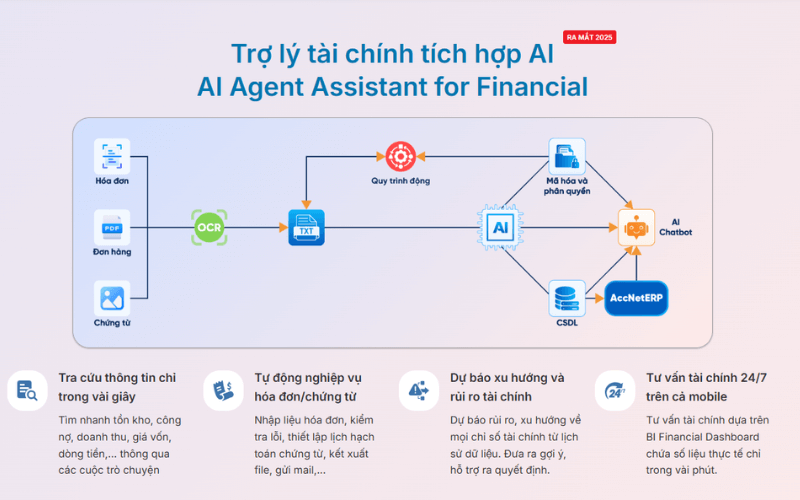
AI in AccNet ERP't just stop at automate data entry, but also:
- Identification & classification certificate from smart: AI scan, read & sort invoice, voucher, receipt, limit errors due to input manually.
- Financial forecasting & budget: the system uses algorithms machine learning to forecast cost, revenue, business support decision fast.
- Warning risk accounting: AI to detect abnormalities in the book, from which timely warning of false or fraud risks.
- Reports assistant smart: AI suggested report template, automatic data aggregation support, leadership, financial analysis instant.
BUSINESS IS WHAT WHEN IMPLEMENTING ACCOUNTING SOFTWARE LAC VIET?
- Experience more than 30 years develop software solutions business management in Vietnam.
- Ecosystem of comprehensive: AccNet ERP easily connect with other solutions of Lac Viet (HRM, Workflow, Portal...).
- Advanced technology: Integrated AI support, cloud & on-premise flexible.
- Services dedicated support: A team of knowledgeable professionals with accounting – finance in Vietnam, companion throughout the deployment.
- Trust from thousands of customers in many areas: finance, banking, manufacturing, trade, services.
Phần mềm Accnet ERP giúp doanh nghiệp hạch toán thuế thu nhập doanh nghiệp chính xác theo pháp lý, đồng thời cung cấp các cảnh báo nhắc nhở thời hạn nộp thuế giúp giảm thiểu rủi ro vi phạm pháp luật.