Accounting for VAT theo Circular 99 là quá trình ghi nhận nghĩa vụ thuế phát sinh từ chênh lệch giữa thuế GTGT đầu ra (TK 3331) và thuế GTGT đầu vào được khấu trừ (TK 133). Cuối kỳ, kế toán thực hiện bút toán kết chuyển Nợ TK 3331 / Có TK 1331 để xác định chính xác số thuế phải nộp. Khi thực hiện nộp tiền vào ngân sách nhà nước qua ngân hàng, kế toán ghi nhận bút toán Nợ TK 3331 / Có TK 112
Accounting VAT is one of the accounting profession important to help businesses declare, manage and pay tax value added correctly. The implementation of the correct accounting entries related not only ensure compliance with legal regulations, but also optimize cash flow, avoid risk of penalties for late payment, errors in financial statements.
For many businesses, especially medium organizations and small, the recognition VAT output/input offset tax deductible and pay tax through a bank or post-processing and settlement often have difficulty if there is no detailed instructions. This article Lac Viet will provide guidance accounting VAT full help accountants easily applied in practice, and enhance effective tax administration, finance.
The general accounting accounting VAT

| Profession | How to account details | Purpose |
| Record input VAT deductible | Debt 152, 155, 621... (depending on the type of expenses, assets) Debt 1331 – VAT is deducted There are 111, 112 – Cash / bank deposit | Recorded the amount of VAT business has paid to supplier, guaranteed to be deducted as tax declaration, the optimal tax obligations, cash flow |
| Record output VAT | Debt 131 – customer receivables Are 511 – sales of goods and services Has 3331 – VAT payable | Reflecting the obligation to pay VAT arising from sale of goods and services helps to declare the exact avoid missing tax |
| Adjust the VAT due to returned goods / discount | Debt 3331 – output VAT Debt 511/521 – revenue/cost related Has 131 – customer receivables | Adjust the amount of tax revenue, exactly when there is a return or discount, reduce errors declaration |
| Accounting VAT payable in the period (the transition period-end) | Debt 3331 – VAT payable Has 1331 – VAT is withheld (if available) | Determine the amount of tax payable in fact states, collated with the declarations and financial statements |
| Payment of VAT via bank | Debt 3331 – VAT payable Are 112 – bank deposits | Recorded obligations tax paid, ensure accounting data joints with realistic, transparent cash flow |
| Clearing VAT also be deducted before | Debt 3331 – VAT payable Has 3331 – VAT is deducted before | Optimal tax obligations, any current, reduce the amount payable to the budget |
| VAT refund from the tax authority | Debt 112 – bank deposits Have 3338 – VAT is completed | Get back the VAT overpaid, optimize cash flow, recorded in the correct accounting data |
| Arrears of VAT after settlement | Debt 821 – the tax Costs (if affected) Has 3331 – VAT payable | Recorded tax obligations and supplemented by the conclusion inspection/check out, avoid risk of penalties for late payment |
| Adjust the VAT reduction after settlement | Debt 3331 – VAT payable Are 821 – the tax Costs or adjusted revenue | Adjust the amount of tax payable upon proof of valid or invoice plugins, ensure accounting data transparency |
1. Overview of accounting for VAT
1.1. Accounting filed what is VAT?
Accounting for VAT (or accounting VAT) is the process recorded the whole number of value-added tax that the business must submit to the state after the projector between output tax and input in the states. This is important profession in order to ensure compliance with tax rules, faithfully reflect financial obligations of the business.
In the accounting system in Vietnam, two accounts used most often in accounting VAT includes:
- Account 133 – VAT is deductible input: used to record the VAT may be deducted when purchasing goods and services for production and business.
- Account 3331 – VAT payable to: reflects the number of business tax payable to The state budget after clearing between output tax and input.
1.2. The accounting principles applied when accounting for VAT

- Input VAT is deductible must have valid documents: Business only entitled to deduct input tax if they meet conditions under the VAT Law: there are legitimate invoices, payments, non-cash against invoices from 20 million or more, goods and services used for business purposes taxable.
- Output VAT must be recorded right time: the Time recorded output tax is the time of invoicing, does not depend on collecting the money. Recording the wrong time can lead to differential tax payable, the risk of penalties for late declaration.
- Collated VAT payable at maturity is mandatory: the End of each declaration, the accountant must collate data between software accounting, tax and ledger TK 133 – 3331. The contrast helps to reduce false before the submission of the declaration, especially for enterprises with multiple invoices input, output during the period.
- Store stock from a full valid: tax authorities have the right to ask businesses to provide records within 10 years. If the lack of records, the entire input tax related may be excluded from deduction. This is the most common cause leading to business is arrears of VAT after inspection.
These principles not only help accounting to comply with regulations, but also bring practical benefits: limiting the risk of arrears, reduce the cost penalty for violation of the declaration, ensure transparency when businesses scale up or participate in the tender.
2. Ways of accounting of VAT output
Output VAT is the number of business tax payable on the value of goods and services sold during the period. This tax amount is calculated by the percentage on the value of payment without tax according to current tax rates (typically 10% in Vietnam). This is the tax required, reflecting the financial obligations of the business for state.
The accounting right output VAT help avoid being declared missing, limiting the risk of tax arrears, late payment penalties, at the same time ensure data on books financial reporting transparency.
2.1 How to account for VAT output according to each case
| Case | How to account |
| Sell goods, services taxable, |
|
| Discounts, trade discounts, sales returns |
|
| Invoice adjustments |
|
2.2 illustrative example according to actual business
Situation: Business, selling products worth $ 500 million, 10% VAT. In the period, the client returns a value of 50 million, 10% tax.
Record journal entries:
- Sales: Debt 131: 550 million / There are 511: 500 million; There are 3331: 50 million
- Returned goods: Debt 3331: 5 million / There are 511: 5 million; Debt 511: 50 million / There are 131: 50 million
Benefits: Thanks to accurately record business for the output tax and easily, to avoid errors when declaring and paying taxes.
3. Accounting for input VAT deductible
3.1. Conditions for deduction of input VAT
Business is only entitled to deduct input tax if it meets the following conditions:
- Valid documents: Invoice, VAT regulations, to have complete information about sellers, goods and services tax.
- Thanh toán không dùng tiền mặt: Có chứng từ thanh toán không dùng tiền mặt đối với hóa đơn từ 5 triệu đồng trở lên (đã gồm thuế GTGT). Ngưỡng này đã giảm từ 20 triệu xuống 5 triệu đồng, áp dụng từ 01/07/2025. (Ngoài ra, theo Luật thuế GTGT số 48/2024/QH15, Nghị định 181/2025/NĐ-CP, Thông tư 69/2025/TT-BTC Đối với hóa đơn trên 20 triệu đồng, thanh toán phải qua ngân hàng hoặc các phương thức thanh toán được pháp luật cho phép.)
- Trường hợp mua trả chậm, trả góp: nếu đến hạn thanh toán theo hợp đồng mà chưa có chứng từ thanh toán không dùng tiền mặt hợp lệ, doanh nghiệp phải kê khai điều chỉnh giảm số thuế GTGT đầu vào đã khấu trừ tương ứng.
- Contract – statistics board – acceptance test records: goods and services must actually serve active production business taxable.
3.2. How to record accounting VAT deductible
Accounting recorded goods and services purchased:
- Debt 152, 155, 621... (depending on the type of expense, asset)
- Debt 1331 – VAT deductible
- There are 111, 112 – Cash or bank money
When the declaration of monthly VAT, the input tax is deducted directly into the VAT number must submit:
VAT payable = output Tax – input Tax-deductible
3.3. Illustrative examples and note when the projector
For example, the Business purchased raw materials worth $ 100 million, 10% VAT, payment through bank:
- Debt 152: 100 million
- Debt 1331: 10 million
- There are 112: 110 million
Note when the projector:
- Collated data between invoicing, accounting, software, tax declaration helps avoid the declare excess or deficiency VAT.
- According to the report, the General department of Taxation 2023, about 28% of businesses experiencing errors when deducting input tax due has not collated valid invoice or wrong TK.
When accounting for the VAT to the correct input, businesses reduce the amount of tax payable, optimize cash flow, ensure compliance with legal provisions, limiting the risk of administrative fines.
4. Accounting VAT payable in the states
4.1. Formula for determining the VAT payable
VAT payable is the tax business is obliged to pay into The state budget in the accounting period. The basic formula is applied:
VAT payable = output VAT – input VAT deductible
In which:
- Output VAT: is the tax arising from the sale of goods, provides services in the states.
- Input VAT is deductible: is corporate tax paid to suppliers, is allowed to deduct according to the regulations.
For example, Corporate tax, VAT output is 50 million and input VAT is deductible is 30 million. Then:
- Tax payable = 50 – 30 = 20 million.
Determining the right amount of tax to be paid to help businesses avoid the risk of arrears, reduce costs, penalties, optimize cash flow tax.
4.2. Pen payment of the transfer tax, VAT, end of period
The accountant performs accounting, tax, VAT, end of the period to determine the amount of tax payable on the ledger:
Pen general accounting:
- Debt TK 3331 – VAT payable
- Have TK 1331 – VAT is withheld (if available)
After the transfer, the balance of TK 3331 show the total amount of VAT business must pay in the states.
Practical benefits:
- Helps accurately collated with the declaration of VAT.
- Ensure business declare and pay tax on time, restrictions, penalties for late payment.
4.3. The case of tax payable or deductible
- Tax must also submit: to Be accounted for in TK 3331 to make tax payment through bank or cashier books.
- Tax is also deductible: Switch to the following period, recorded on TK 1331 to continue deducted when incurred obligations tax in the states of new.
Illustrative example: output Tax: 70 million Tax deductible input: 90 million.
- There is no deductible: 90 – 70 = 20 million, scoring TK 1331 switch states after.
- Numbers must submit = 0.
5. Accounting VAT payable after the settlement
5.1. Tax arrears after check – inspector
When the tax inspector, specify the business has not declared enough tax, accounting to record tax arrears:
Journal:
- Debt 821 – the tax Costs (if affected)
- There are 3331 – VAT payable
For example: Business is collecting 5 million VAT due bills input has not been declared properly. Entry: Debit 821 / There 3331: 5 million.
5.2. Reduced tax payable – adjusted decline after settlement
If, after settlement of the business is reducing the number of tax payable (for example: valid invoice not), accounting record the obligation:
Journal:
- Debt 3331 – VAT payable
- There are 821 – the tax Costs or adjusted revenue, depending on the situation
Practical benefits:
- Adjust timely accounting data, ensure financial reporting transparency.
- Reduce the risk of administrative fines, protect the financial interest of the business.
5.3. For example a real world situation
Situation: Business and declare VAT output is 100 million, the input deductible 80 million → Tax payable 20 million.
- After inspection, the tax authorities determine the 10 million input is not valid, → have to pay an additional 10 million.
- Pen payment arrears: Debt 821 / There 3331: 10 million.
- On the contrary, if the business additional vouchers valid → adjust up: Debt 3331 / There are 821: 10 million.
The accounting full timely after the finalization help optimized business tax obligations, avoid incurring costs beyond the expected.
6. Accounting VAT payment via bank
6.1 process to pay tax on the system eTax
Currently, the majority of businesses in Vietnam made paying taxes, VAT directly via electronic portal eTax of the General department of Taxation, instead of directly in The state budget.
The basic process includes:
- Declare VAT on accounting software and export declarations XML format.
- Login system eTax download declaration XML system.
- Select the method of payment: bank transfer or card.
- System confirm the amount of VAT payable, issuing electronic receipts.
According to the report, the General department of Taxation 2023, more than 85% of organizations and businesses today make VAT payment via bank help reduce transaction time, limiting the risk of errors when the tax declaration.
6.2 accounting details with examples
When make payment of VAT through the bank, accounting record journal entries:
- Debt 3331 – VAT payable
- There are 112 – bank deposits
Accounting is the reduction of tax obligations on ledger after the money has practically moved into The state budget.
Illustrative example
Businesses have the amount of VAT payable in the states is 50 million. After the declaration of confirmation of tax, accounting and make account transfers through the bank. Accounting recorded:
- Debt 3331: 50.000.000
- There are 112: 50.000.000
Practical benefits:
- Ensure accounting data match the actual taxpayer, avoid errors when settlement last year.
- Help business track tax obligations have complete transparency, cash flow, reduce risk penalties for late payment.
7. Accounting VAT payment by offset, tax refund
7.1 Offset against other taxes
In some cases, businesses can use the VAT also be deducted from the previous period to compensate with the amount of tax incurred must submit any current.
Accounting accounting:
- Debt 3331 – VAT payable
- There are 3331 – VAT is deducted before
Illustrative examples:
- VAT payable states this: 40 million
- Number of input tax is also deductible: 15 million
- Done clearing: 40 – 15 = 25 million payable to the budget.
- Accounting accounting:
- Debt 3331: 40.000.000
- There are 3331: 15.000.000
7.2 accounting tax refund when a decision of tax authorities
When a business is tax authorities refund VAT (for example export or be refunded the balance of input tax), accounting recorded:
- Debt 112 – bank deposits (get refund)
- There are 3331 – VAT payable or Has 3338 – VAT be finished custom accounting software
Illustrative example: Business is VAT refund 30 million. Entry:
- Debt 112: 30.000.000
- There are 3338: 30.000.000
Practical benefits:
- Help entrepreneurs optimize cash flow, take advantage of the amount of VAT already paid to serve business activities.
- Increase transparency of accounting data, reducing the risk of errors when solving math and collated with the tax authority.
- Especially useful to the business directory, where the input VAT is often higher than output to a tax refund.
8. Errors frequently encountered when accounting for VAT
In the process of accounting for VAT, many businesses often encounter some errors common. Recognition to avoid errors, this helps reduce the risk of administrative fines, optimal cash flow to ensure transparency of accounting data.
8.1. Accounting teen vouchers to pay tax
One of the flaws common business is recorded tax payable but lack proof of payment or receipt of payment of tax.
- For example: Business declaration of the amount of VAT payable 50 million but forget pen and Debt 3331 / There are 112 when transfer payments to the budget.
- Consequences: the balance on the ledger does not match with bank receipts and reports on system eTax, leading to the risk of inspection, arrears or late payment penalties.
Practical solution:
- Kept fully electronic receipts, invoices, vouchers related.
- Collated bookkeeping with receipts and system ETAX before settlement.
8.2. Not accounting for difference from the previous period
When the number of input tax or output remaining from the previous period, many businesses often forgotten account the number, and this gap in existing states.
- For example: input Tax deduction before the rest 20 million but does not enter into TK 1331 to offsetting this, leading to declare the wrong amount of tax payable.
- According to the survey, the General Tax department 2023, about 22% of business is tax adjustments due to this error in the settlement of VAT.
Practical solution:
- Regularly review the balance TK 1331, TK 3331 end of the period and enter the correct balance to the next month.
- Use accounting software can alert the balance of VAT to reduce the risk of errors.
8.3. Not collated on ETAX
One other flaws are not collated data accounting system, tax declaration ETAX before paying tax.
- For example: Business declare VAT payable 50 million on accounting software but the system ETAX show 52 million due to an invoice has not yet been entered.
- Consequences: When the tax check, businesses can be fined for late payment or tax arrears.
Practical solution:
- Before taxes, collated entire dataset TK 1331, 3331, invoice input, output reports on ETAX.
- Timely updates to the adjustments arising and records journal supplement if needed.
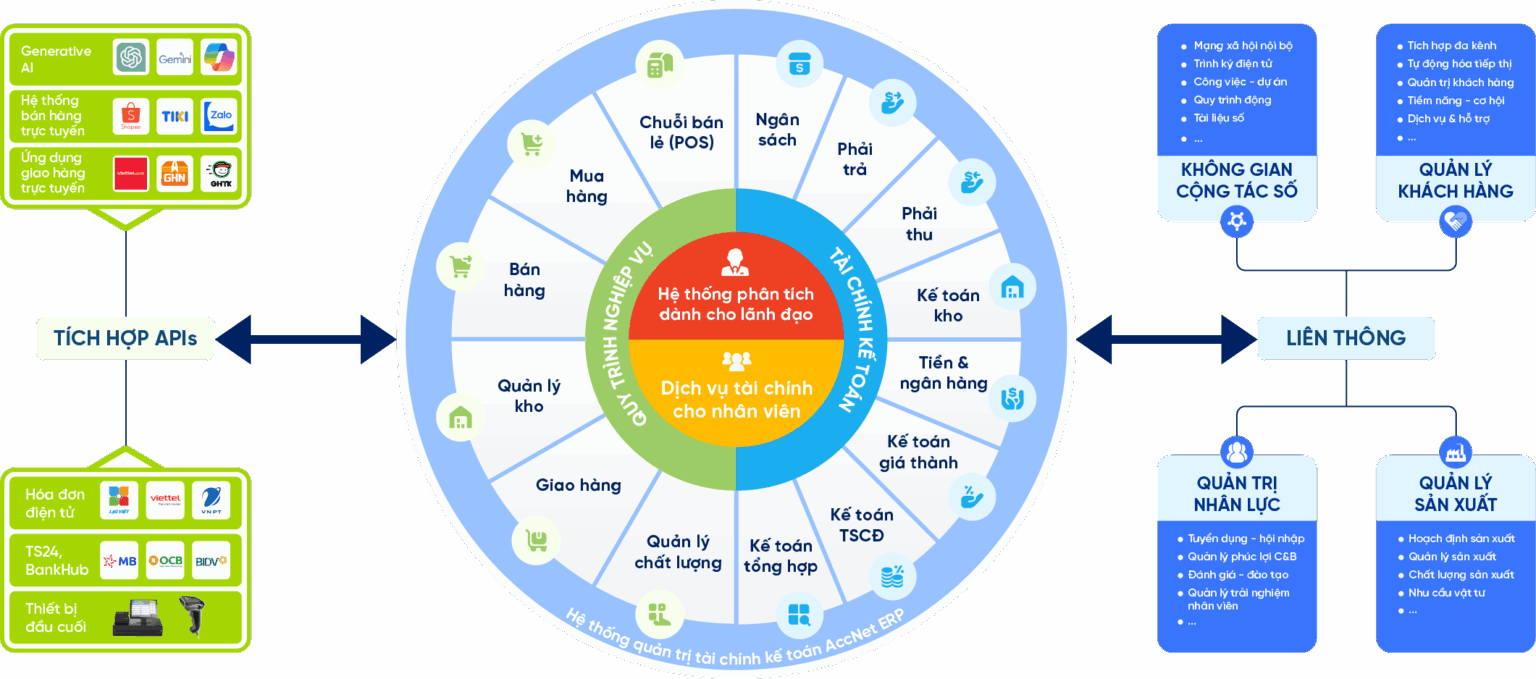
Giải pháp Accnet ERP kế toán toàn diện cho doanh nghiệp
Accnet ERP là accounting software designed to support the organizations and enterprises are looking for solutions, process automation accounting, revenue and expenditure management, tax declaration, VAT correctly transparency.
- Với giao diện thân thiện, Accnet ERP giúp kế toán viên dễ dàng nhập liệu, theo dõi số dư các tài khoản, kết chuyển thuế GTGT cũng như đối chiếu dữ liệu với ngân hàng và hệ thống eTax.
- Điểm mạnh của Accnet ERP không chỉ nằm ở việc tự động hóa các nghiệp vụ kế toán phức tạp, mà còn giúp doanh nghiệp tối ưu dòng tiền, giảm rủi ro sai sót đảm bảo tuân thủ pháp luật.
- For example, when the accounting of VAT, the software will automatically transfer the output tax – input, reminders, deadline, create the accounting standards to help reduce the time to manipulate crafts, increased reliability of financial reporting.
- Nhờ khả năng linh hoạt trong việc tùy chỉnh theo loại hình doanh nghiệp, Accnet ERP trở thành công cụ hữu ích cho cả doanh nghiệp vừa và nhỏ lẫn các tập đoàn lớn giúp kế toán viên tập trung vào phân tích số liệu ra quyết định kinh doanh, thay vì tốn nhiều thời gian cho việc nhập liệu, kiểm tra thủ công.
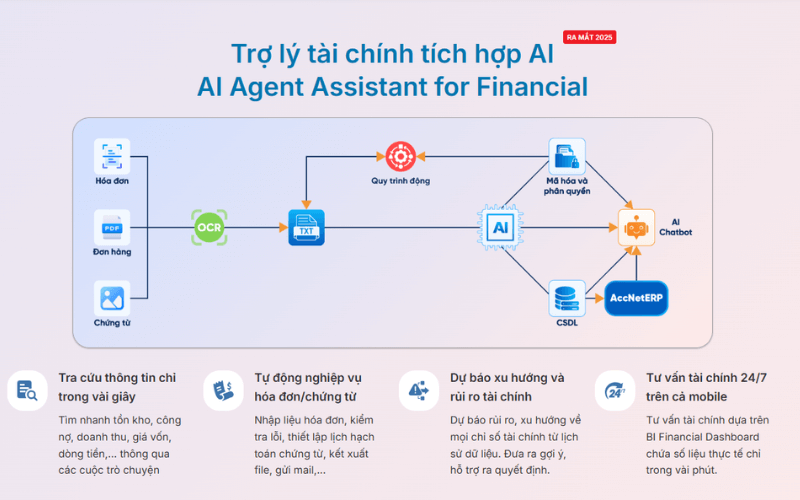
INTEGRATED AI ACCELERATION CONVERTER OF ACCOUNTING
AI in AccNet ERP't just stop at automate data entry, but also:
- Identification & classification certificate from smart: AI scan, read & sort invoice, voucher, receipt, limit errors due to input manually.
- Financial forecasting & budget: the system uses algorithms machine learning to forecast cost, revenue, business support decision fast.
- Warning risk accounting: AI to detect abnormalities in the book, from which timely warning of false or fraud risks.
- Reports assistant smart: AI suggested report template, automatic data aggregation support, leadership, financial analysis instant.
BUSINESS IS WHAT WHEN IMPLEMENTING ACCOUNTING SOFTWARE LAC VIET?
- Experience more than 30 years develop software solutions business management in Vietnam.
- Ecosystem of comprehensive: AccNet ERP easily connect with other solutions of Lac Viet (HRM, Workflow, Portal...).
- Advanced technology: Integrated AI support, cloud & on-premise flexible.
- Services dedicated support: A team of knowledgeable professionals with accounting – finance in Vietnam, companion throughout the deployment.
- Trust from thousands of customers in many areas: finance, banking, manufacturing, trade, services.
Nhận demo miễn phí phần mềm kế toán Lạc Việt để số hóa chuyển đổi quy trình nghiệp vụ kế toán trong doanh nghiệp.
In summary, the accounting of VAT are essential to ensure businesses comply with legislation, manage cash flow, efficiency and optimal tax obligations. The recognition of the full accounting from output tax, input tax, pay the tax through a bank to handle after settlement not only help accountants work exactly, but also increase transparency in financial reporting. Hope the information provided from Vietnam to help the accountant in the accounting profession in business.