
Hạch toán chi phí bán hàng là quá trình tập hợp và ghi nhận toàn bộ các khoản chi phát sinh trực tiếp liên quan đến việc tiêu thụ sản phẩm, hàng hóa hay dịch vụ vào Tài khoản 641 (TK 641). Các khoản chi này (như lương nhân viên bán hàng, quảng cáo, vận chuyển, khấu hao) được phân loại theo các tiểu khoản từ 6411 đến 6418 qua bút toán Nợ TK 641 và Có TK 111/112/331/334/214.
Cuối kỳ kế toán, toàn bộ chi phí phát sinh sẽ được kết chuyển sang TK 911 (Nợ TK 911 / Có TK 641) để xác định chính xác kết quả kinh doanh. Việc hạch toán dồn tích đúng thời điểm và đầy đủ chứng từ giúp doanh nghiệp kiểm soát tốt ngân sách, phản ánh đúng lợi nhuận thuần và hạn chế rủi ro bị truy thu thuế.
Article Lac Viet will provide the concept of standard cost components, for example the actual optimal solution by technology.
1. Understand overview of cost of sales
1.1 Cost of sales is what?
In business accounting, cost of sales được hiểu là toàn bộ khoản chi phát sinh liên quan trực tiếp đến hoạt động tiêu thụ sản phẩm, hàng hóa hoặc dịch vụ. Follow Circular 99/2025/TT-BTC (hiệu lực từ 01/01/2026, thay thế Thông tư 200/2014/TT-BTC), TK 641 và các tiểu khoản 6411-6418 giữ nguyên số hiệu, kết cấu. và Thông tư 133/2016/TT-BTC, các khoản chi này được tập hợp theo dõi trên Tài khoản 641 – Chi phí bán hàng.
In practical perspective, the cost of sales is not merely the recognition of expenses in the books. This is a group of costs in the consumption of business, the level of investment for the customer experience, efficient sales team and the competitiveness of products on the market.
For example, staff Salaries, sales, cost of running ads on Facebook Ads, the cost of shipping goods to customers are included in cost of sales because they attach directly to the sales process.
1.2. The item cost of sales according to accounting regulations
In fact, knowing each item under cost of sales not only help accounting accounting regulations, but also support business leaders cost analysis according to each stage of the sales and evaluate the effectiveness of each activity, such as marketing, sales, shipping or aftermarket.
Below is a detailed analysis of each item according to TK 641 – Cost of sales.
- Cost clerk: This is the cost of the most common, accounting for a large proportion in the total cost of sales of the business, including: salaries, bonuses, sales commissions, allowances, compulsory insurance (SOCIAL insurance, health INSURANCE, UNEMPLOYMENT insurance) of employees, sales staff, customer care, and employee transactions.
- The cost of materials, packaging used for the sale: this Group includes packaging materials, labels, bags, seal sealing, paper guide, or the supplies needed to complete the product before guests.
- Cost utensils sales: includes tools for sales activities such as shelf display POSM (signs, advertising poster), receipt printer, barcode scanning equipment, chair, table, transaction area,...
- Depreciation of fixed assets sales service: This is the cost of depreciation of properties directly used for sales activity, such as automotive, delivery, POS, display cabinet, equipment inventory management software sales (if recorded as fixed assets).
- Cost of product warranty: includes the cost of materials and repair, the cost of rent in addition to warranty service, cost of technical staff or the cost of return located in the warranty policy.
- Cost of services purchased outside: including the services to support the selling process such as transportation, loading and unloading, hire a bonded warehouse service, advertising, online marketing, trading, electronic, commission agents, free COD,...
- The cost in another currency incurred in the sale: This is the group costs are not included in the item on but arises directly in sales activity, as the cost of living, expo, conference, customers, bank fees when collecting...
1.3. Phân biệt chi phí bán hàng (TK 641) và chi phí quản lý doanh nghiệp (TK 642)
Nhầm lẫn giữa hai tài khoản này là lỗi phổ biến (đã nêu ở mục 5.2) – bảng dưới đây tổng hợp lại để tra cứu nhanh:
| Criteria | TK 641 – Chi phí bán hàng | TK 642 – Chi phí quản lý DN |
|---|---|---|
| Purpose | Phục vụ trực tiếp hoạt động tiêu thụ sản phẩm/hàng hóa/dịch vụ | Phục vụ quản lý, điều hành chung toàn doanh nghiệp |
| Ví dụ điển hình | Lương nhân viên bán hàng, quảng cáo, vận chuyển giao hàng, hoa hồng đại lý | Lương bộ phận hành chính/kế toán, chi phí văn phòng, thuế môn bài (trước 2026), tiếp khách chung |
| Bộ phận phát sinh | Phòng kinh doanh/bán hàng, marketing | Ban giám đốc, phòng hành chính-nhân sự, kế toán |
| Ảnh hưởng báo cáo | Trừ trực tiếp vào lợi nhuận gộp để ra lợi nhuận thuần từ bán hàng | Trừ chung vào lợi nhuận thuần hoạt động kinh doanh |
Nguyên tắc phân biệt nhanh: chi phí gắn với việc bán được hàng → TK 641; chi phí để vận hành bộ máy doanh nghiệp dù có bán được hàng hay không → TK 642.
2. Account used when accounting cost of sales
In the system of enterprise accounting, cost of sales is set mainly on account 641 – Cost of sales. This account is used to reflect the full costs incurred in order to serve the sales process and provide service to customers.
Theo TT99/2025/TT-BTC, TK 641 được chia thành các tiểu khoản giúp kế toán theo dõi chi tiết từng nhóm chi phí. Việc tách rõ theo tiểu khoản không chỉ để hạch toán đúng quy định, mà còn giúp doanh nghiệp phân tích từng khoản mục chi phí, đánh giá hiệu quả của từng bộ phận như marketing, sale, chăm sóc khách hàng hay vận hành giao hàng.
The sub-accounts of TK 641 includes:
- 6411 – Cost sales staff
- 6412 – Cost of materials, packaging
- Drill 6413 – Cost tools, utensils sales
- 6414 – Cost depreciation of fixed assets
- 6415 – Cost product warranty
- 6417 – Cost outside service
- 6418 – cash Expenses other
Outdoor TK 641, accounting longer have to use the account other relevant depending on the nature of professional. For example:
- TK 111, 112: payment by cash or bank transfer.
- TK 152, 153: Export supplies, packaging or instruments sales service.
- TK 214: depreciation of fixed assets related to sales activities.
- TK 331: the Cost of services purchased in addition to unpaid (such as shipping, advertising).
3. Principles recorded cost of sales
The recorded cost of sales not merely data entry into software, which must adhere to strict accounting principles to ensure transparency, valid and in the right time. These guidelines are prescribed in the accounting Standards in Vietnam VAS 01 – general principles and VAS 02 – inventory.
Here are the core principles:
3.1. Recorded cost according to the accounting period
Cost of sales must be recorded in the correct accounting period for which the cost that arises, not dependent on time of payment. This is the principle of accrual (accrual basis).
For example, the Business of running ads on Google Ads in 9 months, but payment on January 10. According to standard accounts, this must be recorded at the cost January 9 for related to revenue that month.
Benefits for business:
- Report business results reflect the true fact.
- Leaders avoid misunderstanding that the cost incurred deviation with revenue.
- Help assess the effectiveness each campaign sales according to each states.
3.2. Not recorded cost exceeded a reasonable level
Tax regulations and accounting requirements, cost recorded must be reasonable and valid documents. The expenses exceeding the limit or do not serve direct sales activities will not be counted at a reasonable cost when calculating the tax.
Example common:
- Cost of living exceeds the actual or no bill.
- Marketing costs, no contracts, no stock from electronic payments.
- Cost of roses no statement or confirmation of the recipient.
Enterprise value received in compliance with this principle:
- Avoid the risk of tax arrears and late payment penalties.
- Keep transparency in financial and reputation when auditing or call capital.
- Better control sales budget.
3.3. In accordance with accounting standards in Vietnam (VAS 01, VAS 02)
Accounting standards specified expenses should be recorded when
- Have the ability to reduce the economic benefits in the future.
- Can be determined in a reliable way.
This helps to ensure that the business only recorded in cost of sales when there are clear grounds, avoiding the recorded deviations lead to incorrect statements.
For example:
Business scheduled to be held customer conference in the following month. Though signed the contract, but the event has not yet taken place, accounting has allowed recognition of expenses. Only come when the business receives the service (the test), the cost of new qualified accounting.
Values bring:
- Financial statements “clean”, easy to check, easy to collate.
- Minimize disputes about the data when the audit.
- Help business confidence when announced financial partners, or banks.
4. The accounting entries accounting cost of sales popular
In fact operated business, the accounting cost of sales right and consistently, help the leader board tracking, cash flow control, expense ratio, and assess the effectiveness each sales activity, such as marketing, shipping or commission policy.
Here are 5 group accounting cost of sales incurred the most popular, presented in a way easy to understand and have illustrated examples.
4.1 accounting salary and deductions from salaries of sales staff
Nature business: Salary, bonus, commissions, and the insurance quote for salespeople is the direct costs to generate revenue. Therefore, the entire recorded at TK 6411 – Cost sales staff.
The account details
| Case | Accounting |
| Recorded wages payable clerk |
|
| Extract the account mandatory insurance (SOCIAL insurance, health INSURANCE) |
|
| When salary payments |
|
Illustrative example
January 10, salespeople can:
- Salary: 12.000.000 dong
- Commissions based on sales: 3,000,000
- At the same time business insurance quote 22% (shuttle bus) on insurance premiums is 12.000.000 copper = 2.640.000 dong
Accounting recorded:
- Debt 6411: 15.000.000
- There are 334: 15.000.000
- Debt 6411: 2.640.000
- There are 338: 2.640.000
4.2 accounting for expenses, advertising – marketing
Nature business: advertising Costs, Facebook, Google Ads, TikTok Ads... or design services, run marketing campaigns are expenditures directly sales service, belonging to TK 6417 – Cost outside service.
The account details
| Case | The account |
| Invoice service advertising (unpaid) |
|
| When payment |
|
Illustrative example
Businesses run ads Facebook Ads February 10 worth vnd 25,000,000, receive invoices from Facebook Vietnam.
Accounting recorded:
- Debt 6417: 25.000.000
- There are 331: 25.000.000
4.3 accounting, shipping costs, delivery
Nature business: Cost, delivery, loading and unloading, ship COD or rental units shipping is the cost directly incurred to bring the goods to customers belonging to TK 6417 – Cost outside service.
The account details
| Case | Accounting |
| Invoice freight |
|
| When payment free shipping |
|
Illustrative example: Business sales online recorded cost Ship COD months 10 from Fast Delivery, value 18.000.000 copper.
Accounting accounting cost of sales:
- Debt 6417: 18.000.000
- There are 331: 18.000.000
4.4 accounting for depreciation of fixed assets sales service
Nature business: fixed Assets sales service (POS machine, car delivery, display cabinet...) must be allocated depreciation are from time to time use. Account this genus recorded in TK 6414 – Cost depreciation of fixed assets.
The account details
Recorded depreciation expense each month:
- Debt TK 6414
- Have TK 214 – Depreciation of fixed assets
Illustrative examples: Motorcycle delivery worth 30,000,000, depreciation in 3 years. Depreciation monthly = 30.000.000 / 36 = 833.333 copper.
Journal:
- Debt 6414: 833.333
- There are 214: 833.333
4.5 The shipping cost of sales final
Nature business: the entire cost of sales collection on TK 641 should be the switch to TK 911 – defined business results. This step is to determine the profit or loss in the period.
The account details
Transfer the whole cost of sales:
- Debt TK 911
- Have TK 641
Illustrative examples: January 10 enterprise total cost of sales after the account is 150,000,000.
Pen the switch:
- Debt 911: 150,000,000 and
- There are 641: 150,000,000 and
5. The accounting errors frequently encountered when the accounting cost of sales
The process of accounting for cost of sales ideas, but simply to develop flaws if accounting is not tightly controlled vouchers, cost classification or tracking the moving end of the period. These errors can cause business is cost category when tax settlement, falsifying financial statements, or difficult to properly assess the effectiveness of the sales department – marketing.
Here are 5 most common flaws that accounting in business need special attention.
5.1 recognition of expenses not reasonably exceed the allowed
This is most common mistakes when accounting cost of sales. The cost is recorded excessive in comparison with reality, does not serve directly to sales activity, or located outside the limits are accepted according to the tax rules.
For example predisposed to
- Cost of living is too high but there is no statement or can't prove related to sales activities.
- Marketing costs beyond the plan but there are no reports of campaign efficiency.
- Recorded commission costs for people not related or no contract/written certification.
Consequences business-resistant
- Being kind costs, increase INCOME tax payable.
- The financial statements do not reflect the profit.
- With business are called capital or bank loans, data, lack of transparency is a big risk.
5.2 Confused between cost of sales and cost management business
Many accountants confused between cost of sales (TK 641) and the cost of business management (TK 642) because this item has properties quite similar.
Illustrative example
Errors frequently:
- The cost of electricity, water division's sales record on TK 642.
- The cost of stationery used for the marketing department recorded in TK 642 instead of TK 641.
- Cost management salary business record mistaken into cost of sales.
The harmful effects of this mistake
- False, cost structure, causing business misjudged effective sales department.
- Hard ratio analysis cost of sales on revenue – important indicator for commercial business.
5.3 No vouchers valid
Although business arising fact, but if no bills – contracts – statistics board – certified from payment, shall not be counted as a reasonable cost.
Specific examples
- Advertising cost, Facebook Ads is not there bills by individual payment.
- The shipping cost does not have the votes for delivery or lists freight.
- Cost fairs, workshops't have space rental contract.
Consequences business-resistant
- Do not count on a reasonable cost when calculating corporate INCOME tax.
- Prone to export payment when the tax inspection.
- Affect financial transparency.
5.4 omission marketing costs of and costs technology
Due to the peculiarities of operation of goods, more cost online marketing or software costs yet to be documented in full when accounting cost of sales.
For example errors
- Cost of Google Ads, Tik Tok Ads, cost floor ecommerce't take bills.
- Free software customer care (CRM) software, Email Marketing is not recorded.
- Cost, technology, sales service as chat tools, system landing page to be missed.
5.5 Not the shipping costs, end of period correct process
Many businesses set costs on TK 641 but don't make the pen the switch to TK 911, leading to data backlog and false profits.
Illustrative example
October 10, no cost business sales 250.000.000 but accounting forget the transfer. Report business results will show higher profits reality.
Harm
- False trading results according to states.
- Cause difficulties when financial statements.
- Influence analysis, sales effectiveness over time.
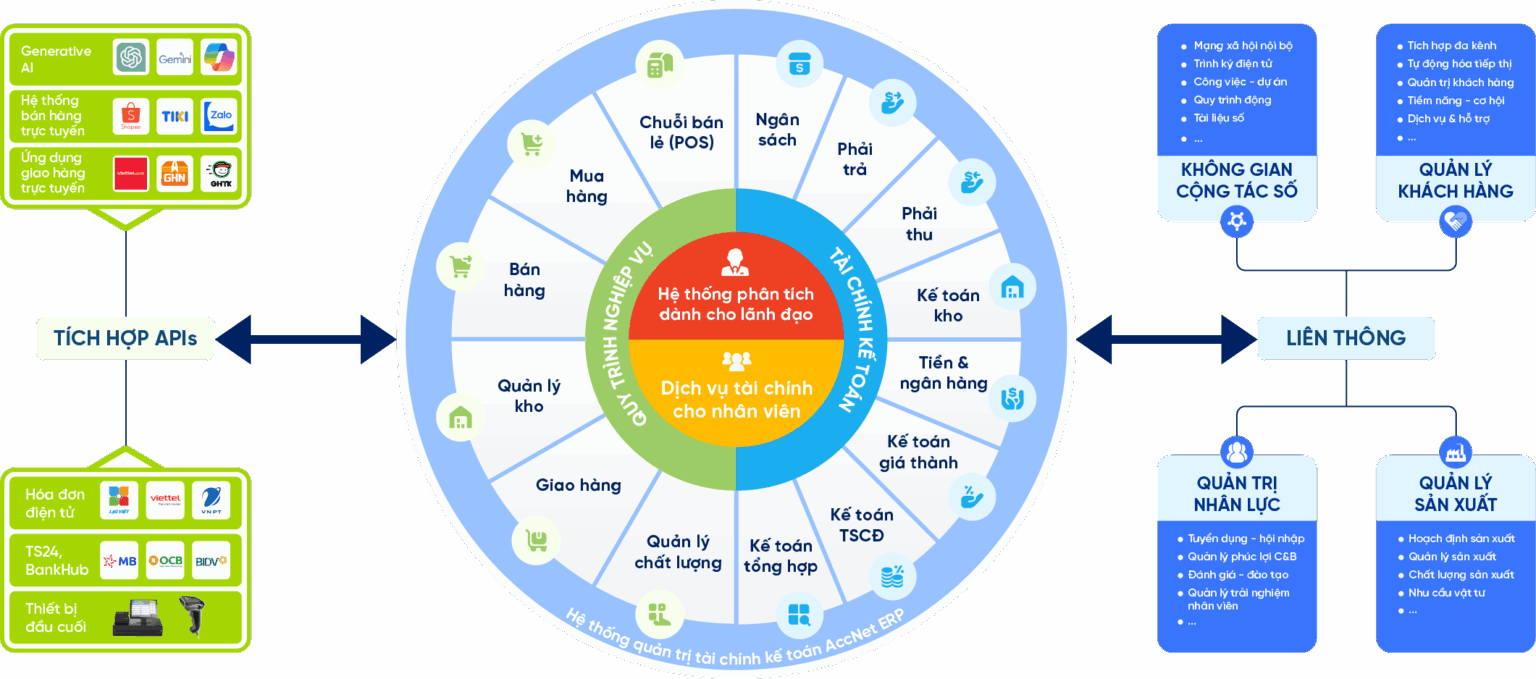
6. Giải pháp Accnet ERP – Hệ thống kế toán số hóa cho doanh nghiệp
In the context of business must handle increasingly more sales data from multi-channel (offline, online, trading, electronic), the accounting cost of sales by manually or dispersed across multiple file Excel makes accounting easy to make a mistake, take the time and difficult to control cost, according to each activity.
Accnet ERP được xây dựng nhằm giải quyết những hạn chế đó bằng cách số hóa toàn bộ hoạt động kế toán và tự động hóa quy trình hạch toán chi phí bán hàng theo đúng chuẩn mực kế toán Việt Nam.
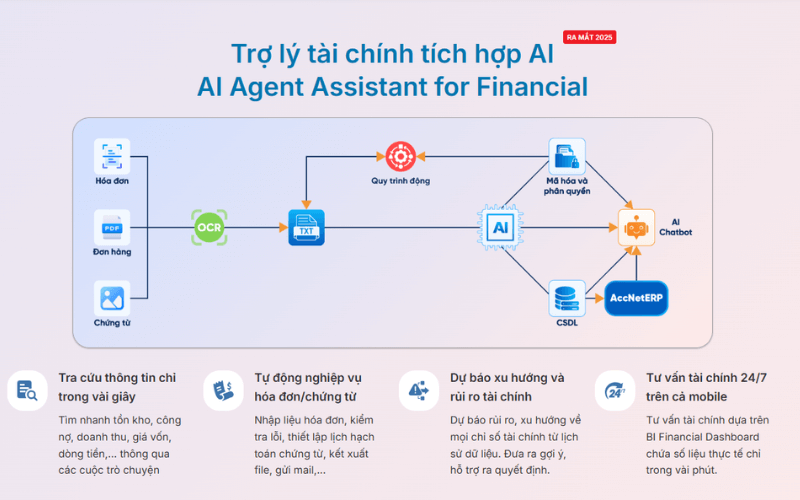
INTEGRATED AI ACCELERATION CONVERTER OF ACCOUNTING
AI in AccNet ERP't just stop at automate data entry, but also:
- Identification & classification certificate from smart: AI scan, read & sort invoice, voucher, receipt, limit errors due to input manually.
- Financial forecasting & budget: the system uses algorithms machine learning to forecast cost, revenue, business support decision fast.
- Warning risk accounting: AI to detect abnormalities in the book, from which timely warning of false or fraud risks.
- Reports assistant smart: AI suggested report template, automatic data aggregation support, leadership, financial analysis instant.
BUSINESS IS WHAT WHEN IMPLEMENTING ACCOUNTING SOFTWARE LAC VIET?
- Experience more than 30 years develop software solutions business management in Vietnam.
- Ecosystem of comprehensive: AccNet ERP easily connect with other solutions of Lac Viet (HRM, Workflow, Portal...).
- Advanced technology: Integrated AI support, cloud & on-premise flexible.
- Services dedicated support: A team of knowledgeable professionals with accounting – finance in Vietnam, companion throughout the deployment.
- Trust from thousands of customers in many areas: finance, banking, manufacturing, trade, services.
Việc thực hiện đúng quy trình hạch toán chi phí bán hàng giúp doanh nghiệp kiểm soát chi phí hiệu quả, tối ưu hóa lợi nhuận đáp ứng đầy đủ yêu cầu pháp lý. Sử dụng các phần mềm kế toán chuyên nghiệp như Accnet ERP sẽ hỗ trợ tự động hóa quá trình hạch toán, giảm thiểu sai sót, tiết kiệm thời gian giúp kế toán viên tập trung vào phân tích, báo cáo và tư vấn chiến lược kinh doanh.