
Hạch toán doanh thu bán hàng là quá trình ghi nhận và phân loại các khoản thu phát sinh từ việc chuyển giao quyền sở hữu hàng hóa hoặc dịch vụ cho khách hàng. Theo quy định kế toán hiện hành (như Circular 99/2025/TT-BTC), doanh thu chỉ được ghi nhận khi có hóa đơn, chứng từ hợp lệ qua bút toán Nợ TK 111/112/131 và Có TK 511, Có TK 3331. Việc hạch toán đúng thời điểm giúp doanh nghiệp phản ánh chính xác kết quả kinh doanh, hạn chế rủi ro phạt thuế, tối ưu hóa quản trị tài chính
This article Lac Viet will provide detailed instructions, accompanied by examples illustrating the important notes so that you can immediately apply in practice, though businesses of every industry.
1. Accounting revenue and principles need to know
1.1 accounting what is revenue?
Accounting for revenue is the process of recognition, classification, tracking the revenue arising from the business activities of the business. Revenue is the primary measure to evaluate its ability to generate profits, operational efficiency of the business.
The type of revenue common include:
- Revenue sale of goods: arising from the sale of products or goods of the business. For example, A retail company phone recognize revenue as soon as the customer payment and receipt of goods.
- Revenues service provider: arise from the provision of professional services such as consulting, training, repair. For example: Business hr consulting revenue recognition upon completion of contract consulting for customers.
- Financial income: includes interest from bank deposits, dividends, profit from financial investments.
- Other sales: revenues generated outside business activities, such as collecting fines contract, sale of fixed assets.
Thus, the accounting of revenue not only is recorded sales revenue, which also includes all the terms that arise related to the economic activity of the enterprise. The correct classification helps financial statements accurately reflect the business situation, decision support effective governance.
1.2 principles of accounting revenue
To account sales, sales revenue, exactly, businesses need to adhere to the principles basic accounting follows:
Principles of revenue recognition:
- Time: revenue is recorded when product ownership or right to use of the service is transferred to the customer.
- Value: revenue should be determined by the actual price obtained, including discounts, rebates, if available.
- Conditions: The revenue accounts must have a legal basis, bills, vouchers valid.
Special cases:
- Revenue prepaid: When businesses get money but not yet implemented service provider account, this is recorded as liabilities (TK 338) and only convert to sales when done.
- Unrealized revenue: For example, service contracts, long-term, revenue is recorded according to progress made.
The correct application of this principle to help businesses avoid errors in accounting, sales management, sales effectiveness, ensure financial statements accurately reflect the actual situation.
2. Way of accounting for revenue in each business

2.1 accounting revenue sale of goods
Revenue sale of goods is the main revenues of the business, commercial manufacturing. This is the revenue arising from the transfer of ownership of goods to customers, with payment obligations. The proper recognition of sales revenue is the foundation important to assess business performance, VAT calculator, determine the profits subject to corporate INCOME tax.
When performing accounting, sales accounting should ensure the full invoice, vouchers and recorded the right time according to the provisions of accounting Standards in Vietnam (VAS 14 – revenue, other income).
How to account
When sales proceeds or grounded revenue recognition:
- Debt TK 111, 112, 131 (Cash/bank deposits/customer receivables)
- Have TK 511 – sales revenue
- Have TK 3331 – VAT payable (if subject to vat)
Business case sales suffered, accounting only recognize revenue upon delivery and customer acceptance of payment.
Illustrative example: company A sells to customers 1,000 products, the unit price 500,000, the total price before tax is vnd 500,000,000. VAT 10%. Payment via bank.
Accounting revenue recognition:
- Debt TK 112: 550.000.000
- Have TK 511: 500.000.000
- Have TK 3331: 50.000.000
Note when accounting
Discount trade discount: deductions revenue must be accounted for in the right account to ensure revenue recorded as net sales.
For example, a discount of 10 million:
- Debt TK 521
- Have TK 131
Sales returns: Upon receipt of returned goods due to technical error or incorrect requirements:
- Debt TK 5212 (sales returns)
- Have TK 131 (or 111,112)
For example: Khách hàng trả lại 50 sản phẩm đã mua (đơn giá 500.000đ/sp, đã gồm thuế GTGT 10%), tổng giá trị trả lại 27,5 triệu đồng (25 triệu chưa thuế + 2,5 triệu thuế GTGT): Nợ TK 5212: 25 triệu / Nợ TK 3331: 2,5 triệu / Có TK 131 (hoặc 111/112): 27,5 triệu.
Revenue recognition the wrong time is a common mistake that business risk tax. According to the General department of Taxation, 22% of the records check to detect deviations due to revenue recognition, the wrong states (source: gdt.gov.vn, inspection report 2023).
2.2. Accounting for revenue service provider
Revenue to provide services that arise when business complete each section, or the entire service obligations under the contract. Other than selling goods and service revenue is often recorded in-progress complete, particularly with regard to long-term contracts such as IT services, consulting, maintenance, transportation.
It is important in accounting for revenue service is to identify the correct section of work was completed to recognize revenue, respectively, avoiding noted ahead of schedule.
How to account
When completed services or partial services are customer approved:
- Debt TK 111, 112, 131
- Have TK 511 – Sales service provider
- Have TK 3331 – VAT output
If the contract is paid in advance, but the service has not completed:
- Debt TK 111,112
- Have TK 3387 – unrealized revenue
Illustrative example
Company B offers services hr consulting, contract price: 100,000,000, VAT 10%. Contract completion, clients transfer payment.
- Debt TK 112: 110.000.000
- Have TK 511: 100.000.000
- Have TK 3331: 10.000.000
Customer case 50% advance payment upon signing the contract:
- Debt TK 112: 55.000.000
- Have TK 3387: 55.000.000
When complete service revenue recognition:
- Debt TK 3387: 55.000.000
- Have TK 511: the 50,000,000
- Have TK 3331: 5.000.000
Note when accounting
- Service revenue should be recognised according to the percentage of completion, avoid notes the whole of the revenue as soon as your money.
- Collation of actual progress with acceptance test records to accurately account.
- With the contract on 1 year, need to set up tables allocate the revenue details under each month, or quarter.
2.3. Accounting financial revenue
Financial revenue is the revenue arising from investment activities financial of the business, such as interest on bank deposits, interest, dividends, profits from investments. This is the portion of revenue not derived from sales activities, providing service, but plays an important role in optimizing cash flow, improve the efficiency of use of funds.
For many business have the money idle or active investing financial strength, the accounting financial turnover is exactly what needed to properly assess the actual profit, control financial risks.
How to account
When business arising revenue finance:
- Debt TK 111, 112: If you receive cash right
- Debt TK 131: If the recorded accounts receivable but not yet earned money
- Have TK 515 – Doanh thu financial activities
A number of commonly encountered:
- Interest on bank deposits
- Interest on loan
- Exchange rate differences interest
- The dividend is divided
- Profit from financial investments short-term or long-term
Illustrative example
Get dividends 50,000,000 from associated companies
- Debt TK 131: the 50,000,000
- Have TK 515: the 50,000,000
Interest on bank deposits 8,000,000, received via bank account
- Debt TK 112: 8.000.000
- Have TK 515: 8.000.000
Business for short-term loans and collect interest 15,000,000
- Debt TK 111/112: 15.000.000
- Have TK 515: 15.000.000
Note when accounting
- Check out the full bank statement or calendar dividend to revenue recognition, the proper states.
- Non-accounting financial turnover in sales revenue in order to avoid bias when analyzing profit.
- For account of interest on delayed payment from the customer (penalties for breach of contract), need to re-classified into other sales not recorded in financial income.
- Theo Thông tư 99/2025/TT-BTC (hiệu lực từ 01/01/2026, thay thế Thông tư 200/2014/TT-BTC). Nguyên tắc trình bày doanh thu tài chính riêng biệt trên báo cáo tài chính không đổi; TK 511, 515, 711 giữ nguyên số hiệu.
2.4. Accounting of revenue other
Revenue other revenues not regular, not arising from the main business activities of the business. These amounts include: collecting fines contract, collect insurance compensation, autumn liquidation of fixed assets, collecting and selling scrap, collected by the customer for compensation...
Though not operate the focus, but other sales need to be accounted for correctly to avoid omission source of guaranteed financial reporting transparency.
How to account
When other sales:
- Debt TK 111, 112: If the money is right
- Debt TK 131: If the recorded accounts receivable
- Have TK 711 – other income
Some typical cases:
- Proceeds from disposal of fixed assets
- Collect penalties for breach of contract
- Income from insurance compensation
- Revenues from the sale of scrap
If related to the liquidation of fixed assets, the need to record the decrease in resource prices, decreased depreciation before recorded other income.
Illustrative example
Liquidation of old machinery price 200,000,000, customer account transfers
- Debt TK 112: 200.000.000
- Have TK 711: 200.000.000
Customers fined for breach of contract 20,000,000
- Debt TK 111: 20.000.000
- Have TK 711: 20.000.000
Selling scrap obtained 5,000,000
- Debt TK 111: 5.000.000
- Have TK 711: 5.000.000
Note when accounting
- Need to establish a full account of asset acceptance report or the decision to dispose of property before the recognition of revenue other.
- With fixed assets liquidation, accounting to record the decrease in fixed assets (TK 211/213), reduced wear and tear (TK 214) pre-recorded earnings.
- The amount of compensation from the insurance should have a proven record of damage (repair bill, memorandum of assessors,...).
- Do not confuse revenue other than accounting sales revenue, to avoid misleading the revenue structure when financial analysis.
3. Accounting for revenue under accounting standards in Vietnam (VAS/IFRS)
Accounting revenue by VAS and IFRS step is important for businesses to ensure financial statements properly reflect the business situation, compliance with legal regulations. The application of accounting standards suitable reducing the risk of errors, the optimal profit to support decision governance.
3.1. Compare VAS and IFRS on revenue recognition
| Criteria | VAS (Vietnam) | IFRS (international) |
| Time recorded | Revenue is recorded when the ownership of the products/services are delivered, the business has the right to collect the money. | Revenue is recognized when control of the product/service delivered to the clients, follow these 5 steps identify revenue (IFRS 15). |
| Classification of revenue | Sales, service delivery, financial and other. | Similar to the VAS, but the emphasis revenue under contracts with customers and the progress made. |
| Report details | Revenue recognition according to each type of business with bills and vouchers in full. | Recognition of revenue under the contract, to allocate contract value if multiple part products or services. |
Illustrative examples:
The company provides training services, long-term contracted 120 million, the time taken 6 months:
- According to VAS: revenue is recorded according to the progress made services can be divided by each month.
- Under IFRS: revenue is recorded based on the control over the progress of the contract, if the contract is divided into many service packs, each pack was recorded separately according to the value of the contract respectively.
3.2. Note the latest changes in legal regulations
- In the year 2024, the Ministry of Finance has updated guidance and recorded sales revenue to provide services, emphasizing revenues must be recorded right time and have the invoice voucher valid.
- The case of revenue received in advance (deposit, payment in advance long-term contract) must be recorded liabilities before moving on to the actual revenue, avoiding the recorded deviations lead to violations of VAT.
- Businesses need to keep track of changes in VAT, corporate INCOME tax related revenue, ensure accounting sales revenue accuracy, reduce the risk of penalties upon audit.
4. A number of accounting errors frequently encountered when accounting and how to fix
Accounting revenue is important profession, but many businesses still encounter the errors common, leading to financial reporting incorrect, tax risk, difficulties in managing cash flow.

Dưới đây là chi tiết những lỗi thường gặp:
| Error | Details |
| Revenue recognition the wrong time |
|
| Not classified revenue right |
|
| Errors in handling discount, discount, returned goods |
|
| Non-compliance with accounting standards |
|
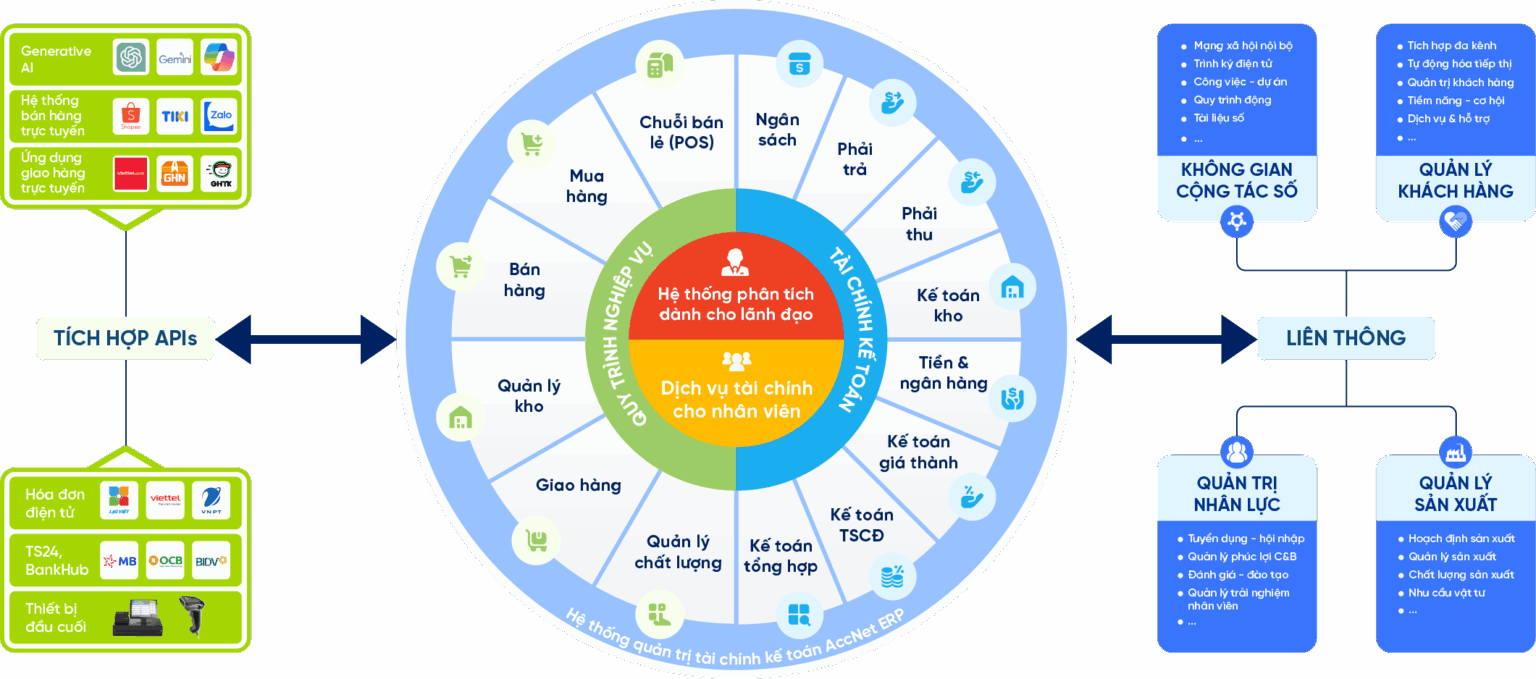
5. Tối ưu quy trình hạch toán với phần mềm kế toán Accnet ERP
Phần mềm Accnet ERP giúp doanh nghiệp khắc phục các lỗi hạch toán doanh thu thường gặp nhờ các tính năng tự động và chuẩn mực:
- Automatic recognition of revenue by time: the System automatically classified sales, revenue, supply services, other sales according to the standard VAS/IFRS, risk reduction noted at the wrong time.
- Manage discount, returned goods: The discount, rebate, discount, returned goods is automatically deducted from revenue, help in accurate reporting.
- Transparency report, detailed analysis: revenue is split by type of service, each customer contracts; support management of cash flow, evaluate business performance.
- Cập nhật chuẩn mực mới: Accnet ERP liên tục cập nhật các quy định mới về hạch toán doanh thu, thuế GTGT và thuế TNDN giúp doanh nghiệp tuân thủ pháp luật.
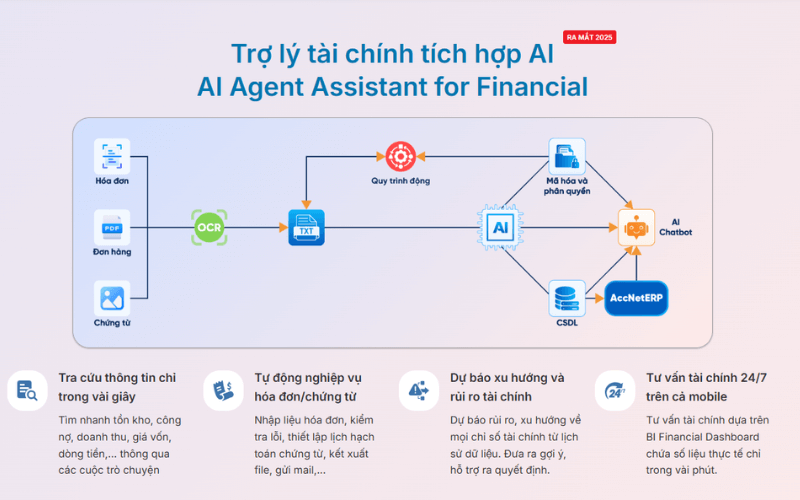
INTEGRATED AI ACCELERATION CONVERTER OF ACCOUNTING
AI in AccNet ERP't just stop at automate data entry, but also:
- Identification & classification certificate from smart: AI scan, read & sort invoice, voucher, receipt, limit errors due to input manually.
- Financial forecasting & budget: the system uses algorithms machine learning to forecast cost, revenue, business support decision fast.
- Warning risk accounting: AI to detect abnormalities in the book, from which timely warning of false or fraud risks.
- Reports assistant smart: AI suggested report template, automatic data aggregation support, leadership, financial analysis instant.
BUSINESS IS WHAT WHEN IMPLEMENTING ACCOUNTING SOFTWARE LAC VIET?
- Experience more than 30 years develop software solutions business management in Vietnam.
- Ecosystem of comprehensive: AccNet ERP easily connect with other solutions of Lac Viet (HRM, Workflow, Portal...).
- Advanced technology: Integrated AI support, cloud & on-premise flexible.
- Services dedicated support: A team of knowledgeable professionals with accounting – finance in Vietnam, companion throughout the deployment.
- Trust from thousands of customers in many areas: finance, banking, manufacturing, trade, services.
Đăng ký demo ngay Accnet ERP ngay hôm nay để tự động hạch toán doanh thu, kiểm soát dòng tiền, tối ưu hiệu quả quản lý tài chính doanh nghiệp.
Câu hỏi thường gặp về hạch toán doanh thu bán hàng
- Doanh thu bán hàng được ghi nhận khi nào?
Khi quyền sở hữu hàng hóa/dịch vụ đã chuyển giao cho khách hàng và doanh nghiệp có quyền thu tiền, có hóa đơn/chứng từ hợp lệ – theo nguyên tắc tại mục 1.2.
- Doanh thu bán hàng (TK 511) khác doanh thu tài chính (TK 515) như thế nào?
Doanh thu bán hàng đến từ hoạt động kinh doanh chính; doanh thu tài chính đến từ lãi tiền gửi, cổ tức, chênh lệch tỷ giá – không được ghép chung, phải trình bày riêng trên báo cáo tài chính (mục 2.3).
- Khách hàng thanh toán trước khi giao hàng có được ghi nhận doanh thu ngay không?
Không. Khoản tiền nhận trước ghi vào TK 3387 (Doanh thu chưa thực hiện) cho đến khi hoàn thành nghĩa vụ giao hàng/dịch vụ mới chuyển thành doanh thu – theo ví dụ tại mục 2.2.