
The type of allowance is not SOCIAL là những khoản tiền hỗ trợ người lao động bù đắp chi phí phát sinh trong quá trình làm việc mà không phải tính vào tiền lương đóng bảo hiểm bắt buộc. Các loại phụ cấp không đóng BHXH 2026 bao gồm phụ cấp ăn trưa, xăng xe, điện thoại, internet phục vụ công việc, cùng các khoản hỗ trợ thâm niên hoặc trách nhiệm đặc thù. The classification accuracy of this account is to help businesses optimize operating costs, comply with legislation and improve the cohesion of the staff.
In operation personnel administration, allowance is an important part of remuneration policy the welfare of the business. Allowances not only help encourage employees to work efficiently, but also reflect the interest of the business to the real needs of workers, as travel expenses, lunch, phone or seniority.
However, not all types of allowances are mandatory social insurance (SI). The classification accuracy of the allowances to help businesses optimize cost and transparency in management, personnel management, at the same time avoid the legal risks as the agency of SOCIAL insurance check.
This article Lac Viet will provide a list of the kinds of allowances't get to explain in detail each item and attached example illustrates the fact, noted important legal help business organizations can effectively apply in the year 2026.
1. Allowances not SOCIAL, what is?
Allowances not SOCIAL is the amount businesses pay more for labor, but not calculated into wages to SOCIAL insurance contribution required. The goal of the allowances this is support workers perform the work, compensate the costs incurred in the process of work that does not affect the SOCIAL insurance fund.
Distinguished allowance to SOCIAL insurance contribution
| Allowance, SOCIAL insurance contribution | Allowances not SOCIAL |
| Include the allowances calculated on the basic salary or bonuses have high wages, for example: the allowance position of supplies, work, reward productivity. The account will be charged to the salary of SI required. | Usually the account supports the fact, for example, allowances for lunch, gasoline, telephone service jobs, allowances responsibility peculiarities. The account is not calculated into wages, SOCIAL enterprises need to declare clearly and in compliance with the regulations (if any). |
Illustrative examples easy to understand
Doanh nghiệp A chi trả 1.500.000 VNĐ/tháng cho nhân viên làm phụ cấp ăn trưa và 1.000.000 VNĐ/tháng cho phụ cấp đi lại. Khoản tiền này không phải đóng BHXH, đồng nghĩa với việc doanh nghiệp không phải tính khoản đóng BHXH bắt buộc trên các khoản này, với điều kiện chúng được ghi thành mục riêng trong hợp đồng lao động, giúp tiết kiệm chi phí đáng kể mà vẫn đảm bảo quyền lợi cho nhân viên.
2. Danh sách các loại phụ cấp thường gặp trong quản lý phúc lợi
Các tổ chức, doanh nghiệp đang tìm hiểu thông tin về các loại phụ cấp không đóng BHXH thường quan tâm đến những khoản phụ cấp nào thực sự không phải đóng BHXH, vừa giúp tối ưu chi phí, vừa đảm bảo quyền lợi nhân viên. Dưới đây là các khoản phổ biến năm 2026 kèm hướng dẫn áp dụng:
2.1 allowances lunch ca
This is the amount of money businesses pay to support staff meals during working hours. Allowances are intended to ensure energy work, increase performance, reduce absenteeism without permission, due to personal reasons.
Lưu ý pháp lý: Theo mục 2 Công văn 1198/CTL&BHXH-BHXH, tiền ăn giữa ca là chế độ phúc lợi khác, không tính vào tiền lương đóng BHXH khi được ghi thành mục riêng trong hợp đồng lao động.
Ví dụ thực tế: Doanh nghiệp A chi trả 1.200.000 VNĐ/tháng/nhân viên cho phụ cấp ăn trưa. Nhờ vậy, nhân viên được hỗ trợ chi phí, ghi thành mục riêng trong hợp đồng, khoản 1.200.000 VNĐ/tháng này không bị tính vào tiền lương đóng BHXH.
Benefits: Reduce the cost of SOCIAL insurance and improved the experience of staff and increase the level associated with the business.
2.2 allowance gasoline car, go back
Allowances are intended to support travel costs for staff when working at the company, or make work, work outside the office.
Conditions are not SI:
- Allowances must pay as agreed in the labor contract or statute bonus.
- Hợp đồng lao động ghi khoản này thành mục riêng (chế độ và phúc lợi khác), nêu rõ tên khoản, mức hỗ trợ và điều kiện hưởng.
Illustrative example: employee B is supported 1,500,000 VND/month for travel expenses. This doesn't have to pay SOCIAL insurance contribution, help businesses significantly reduce the cost must pay SOCIAL insurance monthly.
2.3 mobile phone allowance, internet service job
Explanation: this funding is intended to cover the cost of phone or internet use for work, such as calling customers, exchange, internal or access software remote work.
Conditions apply:
- Allowances apply only when proof of service work.
- Does not apply to personal expenses.
Benefits: Helps our staff to work effectively, at the same time business is not incurring costs of SOCIAL insurance on allowances this budget-saving.
For example: employee C is supported 500.000 VND/month for the cost of phone and internet. This doesn't to pay SOCIAL insurance contribution.
2.4 allowance of responsibility, seniority
This is allowance for the position assumed responsibility over, or for longtime employees to recognize contributions.
Conditions are not SI:
- Phụ cấp trách nhiệm, thâm niên thường là phụ cấp lương, phải tính vào tiền lương đóng BHXH khi được thỏa thuận trong hợp đồng lao động và trả thường xuyên, ổn định. Chỉ phần biến động theo năng suất, quá trình làm việc, chất lượng thực hiện công việc mới không tính.
- Businesses need clear rules in regulation of salary bonus.
Ví dụ minh họa: Nhân viên D làm việc trên 10 năm được hưởng phụ cấp thâm niên 1.000.000 VNĐ/tháng. Do khoản này được trả cố định hằng tháng theo hợp đồng nên vẫn tính vào tiền lương đóng BHXH.
2.5 other allowances not SOCIAL
Giải thích: Bao gồm các khoản đặc thù ngành nghề hoặc thỏa thuận riêng, bao gồm các khoản hỗ trợ, trợ cấp khác được ghi thành mục riêng trong hợp đồng lao động theo khoản 5 Điều 3 Thông tư 10/2020/TT-BLĐTBXH.
Note to apply 2025:
- Must be based on labor contracts, statutes, salaries and bonuses of the business.
- To comply with the Decree, the latest circular to avoid legal risks.
For example: Phụ cấp độc hại, nguy hiểm thường vẫn tính vào tiền lương đóng BHXH nhưng không tính vào thu nhập chịu thuế TNCN theo điểm c khoản 2 Điều 3 Luật Thuế thu nhập cá nhân số 109/2025/QH15.
3. Các loại phụ cấp không phải đóng BHXH theo hướng dẫn của Bộ Nội vụ
Mục 2 đã giải thích từng nhóm phụ cấp thường gặp. Để biết chính xác khoản nào không phải đóng BHXH, doanh nghiệp cần dựa vào cách pháp luật xác định tiền lương làm căn cứ đóng BHXH và danh sách các khoản được hướng dẫn riêng. Mục này tóm tắt hai căn cứ đó, sau đó chỉ ra những loại phụ cấp thường vẫn phải đóng BHXH.
3.1. Căn cứ xác định tiền lương đóng BHXH từ ngày 01/7/2025
Theo Điều 31 Luật Bảo hiểm xã hội số 41/2024/QH15, với người lao động hưởng lương do người sử dụng lao động quyết định, tiền lương tháng làm căn cứ đóng BHXH bắt buộc gồm ba thành phần: mức lương theo công việc hoặc chức danh, phụ cấp lương và các khoản bổ sung khác. Khoản 1 Điều 7 Nghị định 158/2025/NĐ-CP hướng dẫn chi tiết từng thành phần này.
- Về phụ cấp lương, đó là khoản bù đắp yếu tố về điều kiện lao động, tính chất phức tạp của công việc, điều kiện sinh hoạt và mức độ thu hút lao động mà mức lương chưa tính đến hoặc tính chưa đầy đủ, được thỏa thuận trong hợp đồng lao động. Khoản phụ cấp lương phụ thuộc hoặc biến động theo năng suất lao động, quá trình làm việc và chất lượng thực hiện công việc của người lao động không thuộc nhóm này.
- Về các khoản bổ sung khác, điểm c khoản 1 Điều 7 yêu cầu khoản đó xác định được mức tiền cụ thể cùng với mức lương, được thỏa thuận trong hợp đồng lao động và trả thường xuyên, ổn định trong mỗi kỳ trả lương. Khoản bổ sung phụ thuộc hoặc biến động theo năng suất lao động, quá trình làm việc và chất lượng thực hiện công việc cũng không tính vào tiền lương đóng BHXH.
Từ hai quy định trên, doanh nghiệp có thể kiểm tra một khoản tiền bằng ba câu hỏi. Khoản đó có bù đắp điều kiện lao động hoặc tính chất công việc gắn với vị trí của người lao động không? Khoản đó có mức tiền cố định và được trả đều trong mỗi kỳ lương không? Khoản đó có thay đổi theo kết quả làm việc trong kỳ không? Nếu khoản tiền gắn với công việc, cố định và trả đều, khoản đó thường thuộc tiền lương đóng BHXH. Nếu khoản tiền chỉ phát sinh theo kết quả làm việc, hoặc thuộc nhóm chế độ và phúc lợi được hướng dẫn riêng ở mục 3.2, khoản đó không bị tính vào mức đóng.
3.2. Danh sách các khoản không phải đóng BHXH khi ghi thành mục riêng trong hợp đồng lao động
Tại mục 2 Công văn 1198/CTL&BHXH-BHXH năm 2025, Cục Tiền lương và Bảo hiểm xã hội (Bộ Nội vụ) hướng dẫn rằng các chế độ và phúc lợi khác được ghi thành mục riêng trong hợp đồng lao động theo khoản 5 Điều 3 Thông tư 10/2020/TT-BLĐTBXH không phải là tiền lương làm căn cứ đóng BHXH bắt buộc. Theo khoản 5 Điều 3 Thông tư 10/2020/TT-BLĐTBXH, nhóm này gồm 14 khoản cụ thể và các khoản hỗ trợ, trợ cấp khác:
| Nhóm | Các khoản không phải đóng BHXH |
|---|---|
| Enjoy | Tiền thưởng theo Điều 104 Bộ luật Lao động; tiền thưởng sáng kiến |
| Ăn uống, đi lại, liên lạc | Tiền ăn giữa ca; hỗ trợ xăng xe; hỗ trợ điện thoại; hỗ trợ đi lại |
| Nhà ở, gia đình | Tiền nhà ở; tiền giữ trẻ; hỗ trợ nuôi con nhỏ |
| Hiếu hỉ | Hỗ trợ khi người lao động có thân nhân chết; hỗ trợ khi người lao động có người thân kết hôn; hỗ trợ nhân dịp sinh nhật của người lao động |
| Trợ cấp khó khăn | Trợ cấp cho người lao động gặp hoàn cảnh khó khăn khi bị tai nạn lao động; trợ cấp cho người lao động gặp hoàn cảnh khó khăn khi bị bệnh nghề nghiệp |
| Other | Các khoản hỗ trợ, trợ cấp khác được ghi thành mục riêng trong hợp đồng lao động |
Điều kiện then chốt là ghi thành mục riêng. Hợp đồng lao động nên tách phần “Chế độ và phúc lợi khác” khỏi phần mức lương và phụ cấp lương, mỗi khoản ghi rõ tên, mức hỗ trợ và điều kiện được hưởng. Ví dụ minh họa: hợp đồng ghi riêng “Hỗ trợ tiền ăn giữa ca: 1.200.000 đồng/tháng” và “Hỗ trợ xăng xe: 500.000 đồng/tháng” tại mục chế độ và phúc lợi khác. Hai khoản này không cộng vào tiền lương đóng BHXH, nên mức đóng chỉ tính trên mức lương và phụ cấp lương của người lao động.
Nếu hợp đồng gộp các khoản đó vào mục lương, hoặc trả cố định như một phần của lương, cơ quan BHXH có thể xác định đó là tiền lương và yêu cầu đóng bổ sung (xem thêm mục 5.2). Khi hợp đồng của doanh nghiệp có tên khoản tiền không trùng với danh sách trên, doanh nghiệp cần xem bản chất khoản tiền theo ba câu hỏi ở mục 3.1 trước khi quyết định có tính đóng BHXH hay không.
3.3. Các loại phụ cấp thường vẫn phải đóng BHXH
Nhiều doanh nghiệp nhầm các khoản phụ cấp gắn với công việc là phúc lợi. Theo định nghĩa phụ cấp lương tại khoản 1 Điều 7 Nghị định 158/2025/NĐ-CP, những khoản bù đắp điều kiện lao động, tính chất phức tạp của công việc, điều kiện sinh hoạt hoặc mức độ thu hút lao động, nếu được thỏa thuận trong hợp đồng lao động và trả thường xuyên, ổn định, thuộc tiền lương đóng BHXH. Bảng dưới đây tóm tắt các loại phụ cấp thường gặp:
| Loại phụ cấp | Nature | Cách xử lý BHXH |
|---|---|---|
| Phụ cấp chức vụ, chức danh | Gắn với vị trí công việc | Thường tính đóng BHXH khi thỏa thuận trong hợp đồng và trả thường xuyên |
| Phụ cấp trách nhiệm | Gắn với mức độ trách nhiệm của công việc | Thường tính đóng BHXH |
| Phụ cấp độc hại, nguy hiểm | Bù đắp điều kiện lao động | Thường tính đóng BHXH |
| Phụ cấp thâm niên | Gắn với thời gian làm việc, thường trả cố định hằng tháng | Thường tính đóng BHXH nếu trả cố định, ổn định |
| Phụ cấp khu vực, lưu động, thu hút | Bù đắp điều kiện sinh hoạt, mức độ thu hút lao động | Thường tính đóng BHXH |
| Phụ cấp chuyên cần, thưởng hiệu quả thay đổi theo kết quả làm việc | Phụ thuộc quá trình làm việc, chất lượng thực hiện công việc | Không tính vào tiền lương đóng BHXH |
Cùng một tên gọi nhưng cách trả khác nhau có thể dẫn đến kết quả khác nhau. Ví dụ minh họa: doanh nghiệp A trả “phụ cấp trách nhiệm” 1.000.000 đồng/tháng cho trưởng nhóm, ghi trong mục phụ cấp lương của hợp đồng và trả đều mọi tháng, nên khoản này tính vào tiền lương đóng BHXH. Doanh nghiệp B chỉ trả khoản “phụ cấp trách nhiệm” theo kết quả đánh giá từng tháng và mức tiền thay đổi theo kết quả, nên khoản này thuộc nhóm phụ thuộc vào quá trình và chất lượng làm việc, không tính vào mức đóng.
Mỗi loại phụ cấp có những tình huống riêng. Bạn có thể xem hướng dẫn chi tiết về phụ cấp trách nhiệm có phải đóng bảo hiểm không, phụ cấp độc hại có đóng BHXH không and cách tính phụ cấp thâm niên. Phần tiếp theo trình bày các lưu ý pháp lý khi doanh nghiệp áp dụng những quy định này.
4. Các lưu ý pháp lý khi áp dụng các khoản phụ cấp không đóng BHXH
When applying the allowances not SOCIAL institutions, businesses are finding out information about the type of allowance is not SOCIAL to note the legal provisions to avoid audit risk, disputes with employees to ensure transparency in personnel management.
4.1. Tham khảo văn bản pháp luật mới nhất
Allowances are not paying SOCIAL insurance should be based on the current regulations, including:
- Law of 41/2024/QH15 specify the amount to pay to return the item support does not count. With effect from January 01, 7 year 2025.
- Decree 158/2025/ND-CP detailed instructions on SI.
- Decree 02/2025/ND-CP to amend and supplement a number of things about health INSURANCE.
- Công văn 1198/CTL&BHXH-BHXH năm 2025 của Cục Tiền lương và Bảo hiểm xã hội (Bộ Nội vụ) và Thông tư 10/2020/TT-BLĐTBXH về nội dung hợp đồng lao động.
Note 3 the Decree implementing the Law on social insurance lapsed from 01/07/2025:
- Decree 115/2015/ND-CP: guide SOCIAL insurance mandatory. Effective: 01/01/2016. Expire: 01/07/2025. Replaced by: Decree 158/2025/ND-CP
- Decree 143/2018/ND-CP: guide SOCIAL insurance mandatory for foreign workers in Vietnam. Effect: 01/12/2018. Expire: 01/07/2025. Replaced by: Decree 158/2025/ND-CP
- Decree 33/2016/ND-CP: guide SOCIAL insurance mandatory for military personnel, public safety and the weak muscles salary as military personnel. Effect: 26/06/2016. Expire: 01/07/2025. Replaced by: Decree 157/2025/ND-CP
At the same time, the Law on social insurance 2014 expires been replaced by the Law on social insurance 2024, with effect from 01/07/2025.
4.2. Tránh rủi ro kiểm toán và tranh chấp
If allowances are paid incorrectly specified or there is no evidence from transparency, businesses can see:
- Audit SOCIAL insurance: agency may close additional accounts on SOCIAL insurance, if you determine the allowances actually pay.
- Disputes with employees: employees may require additional INSURANCE or compensation if rights are affected.
5. So sánh các khoản phụ cấp không đóng BHXH và không đóng thuế TNCN
Many businesses confuse allowances are not SOCIAL and do not close the personal income tax (PIT). The clear distinctions to help optimize cost and management remuneration policy of transparency.
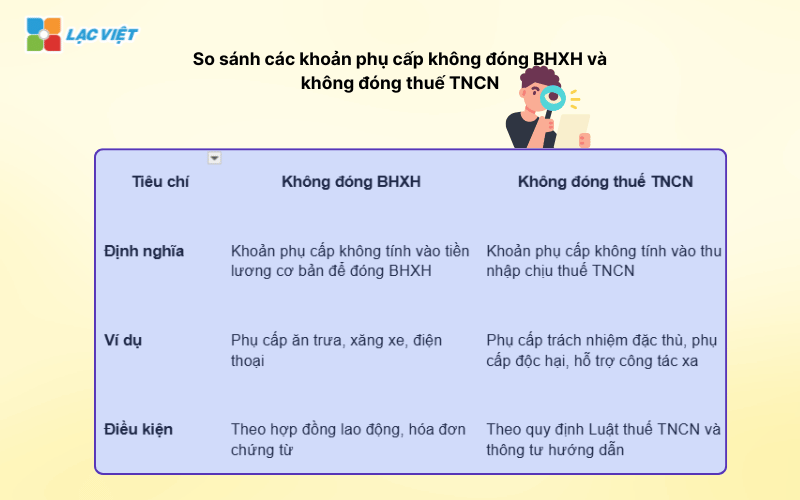
5.1 Phân biệt phụ cấp không đóng BHXH vs không đóng thuế TNCN
| Criteria | No SI | Do not close the PIT |
| Definition | Allowances not included in base salary to SOCIAL insurance contribution | Allowances don't count on income subject to personal income tax |
| For example | Lunch allowances, gasoline, telephone | Allowances responsibility peculiarities, allowance toxic, support the far |
| Conditions | According to labor contracts, bills, vouchers | In accordance with the Law on personal income tax and circular instructions |
| Value for business | Cost savings of SI | Reduced tax liabilities for employees, keeping employee satisfaction |
5.2 Các khoản phụ cấp vừa không đóng BHXH, vừa không đóng thuế TNCN 2025
Some of the most popular, the year 2025 just don't get to just not pay personal income tax, business help optimize costs, and improve employee benefits:
- Travel allowances, lunch, according to the regulations and bills to prove the fact.
- Mobile phone allowance, internet service work.
- Allowances work away in the scope of the actual cost.
Ví dụ minh họa: Doanh nghiệp B chi trả 1.000.000 VNĐ/tháng cho nhân viên phục vụ điện thoại và internet làm việc từ xa. Khoản này không tính vào tiền lương đóng BHXH khi ghi thành mục riêng trong hợp đồng; về thuế TNCN, chỉ phần không vượt mức khoán chi theo điểm đ khoản 2 Điều 8 Nghị định 253/2026/NĐ-CP mới không tính vào thu nhập chịu thuế.
6. Quản lý phúc lợi toàn diện với Lạc Việt SureHCS HRM
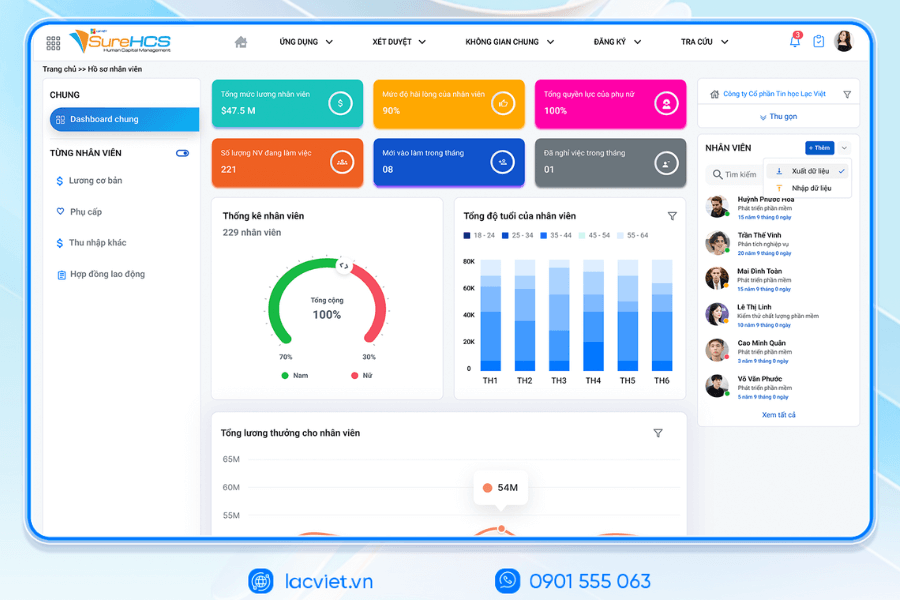
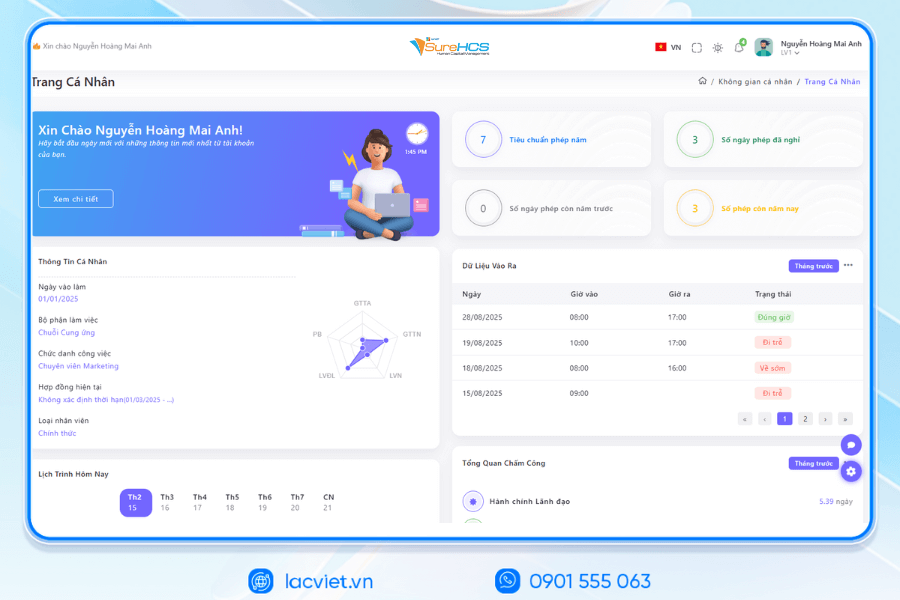
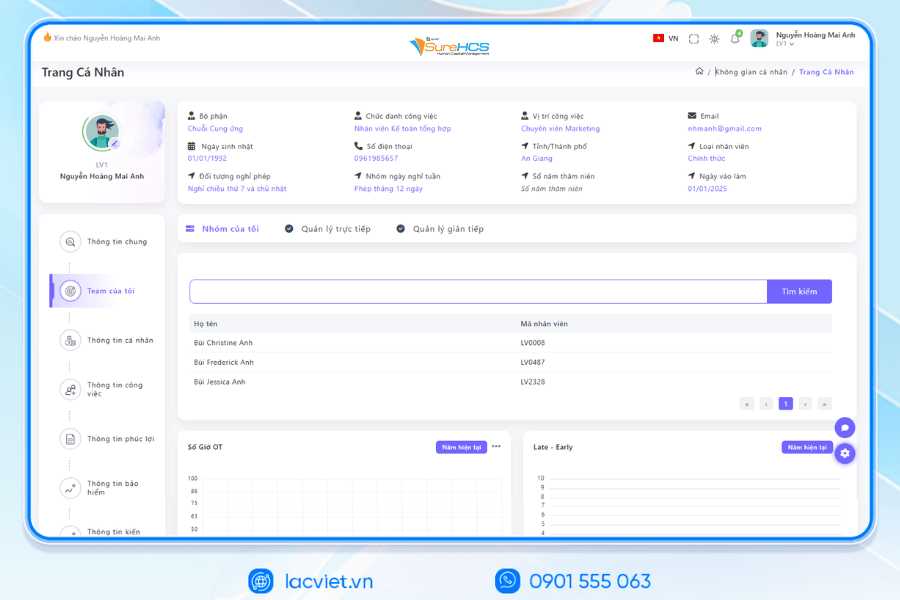
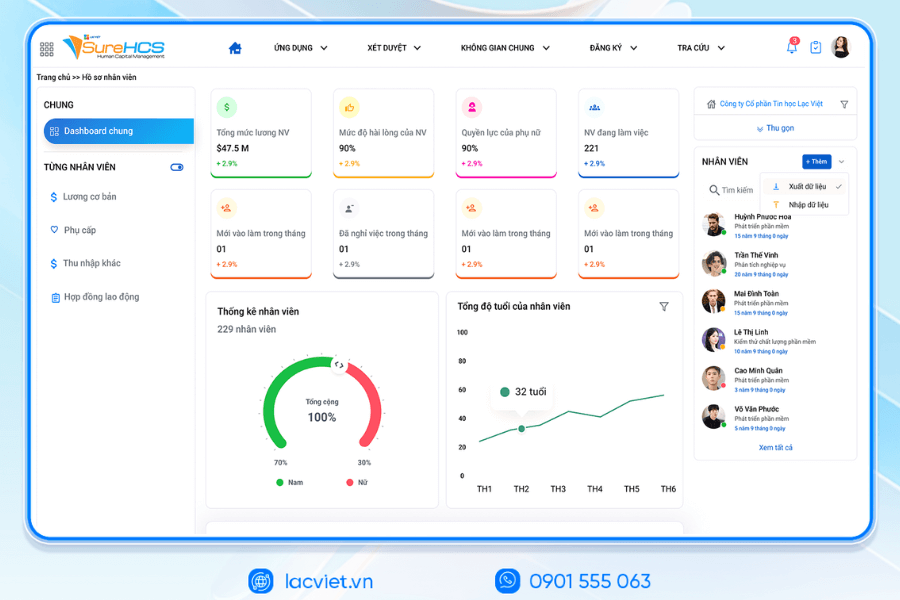
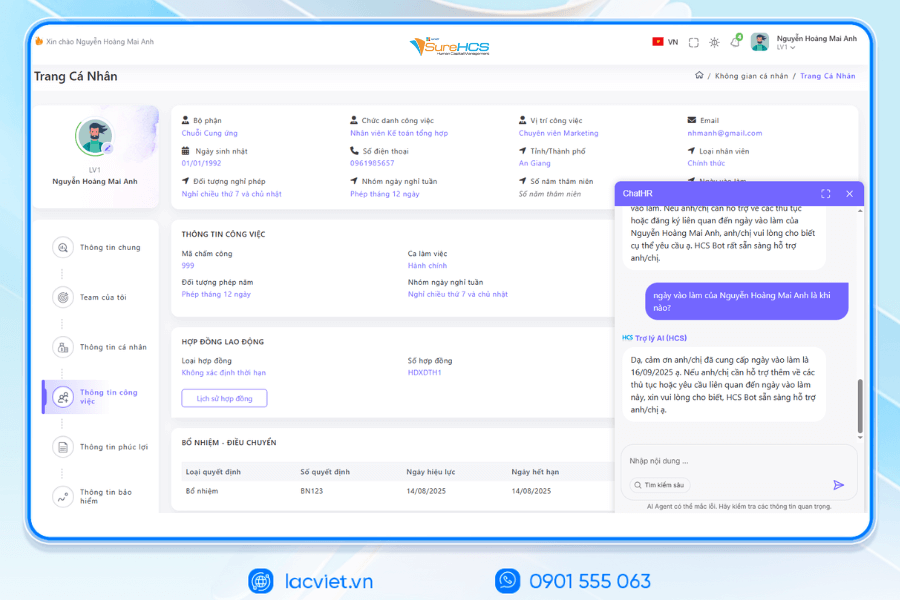
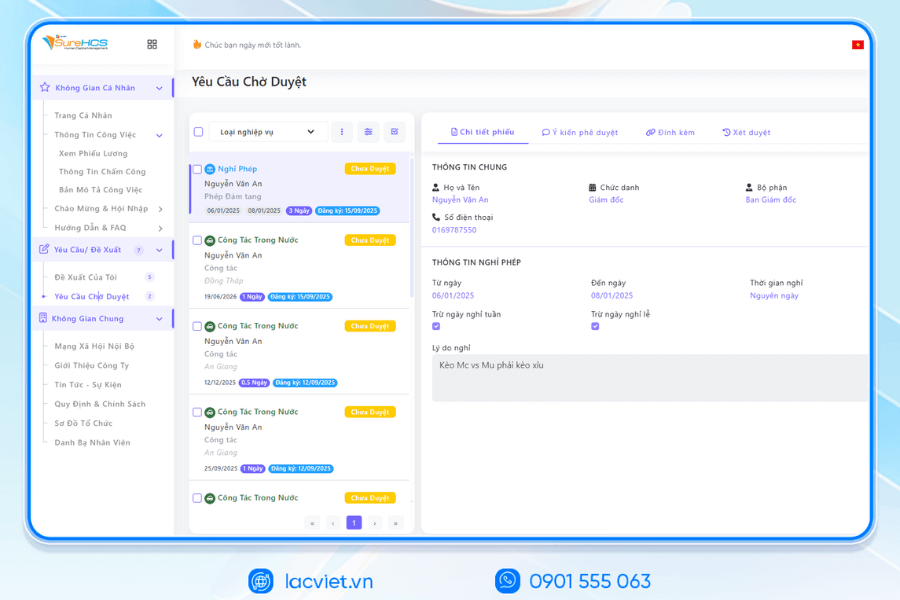
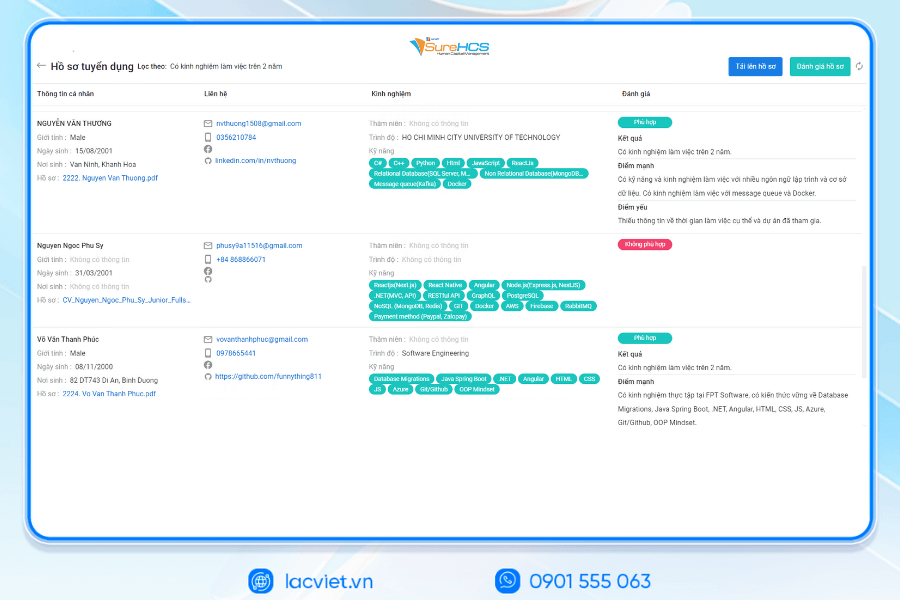
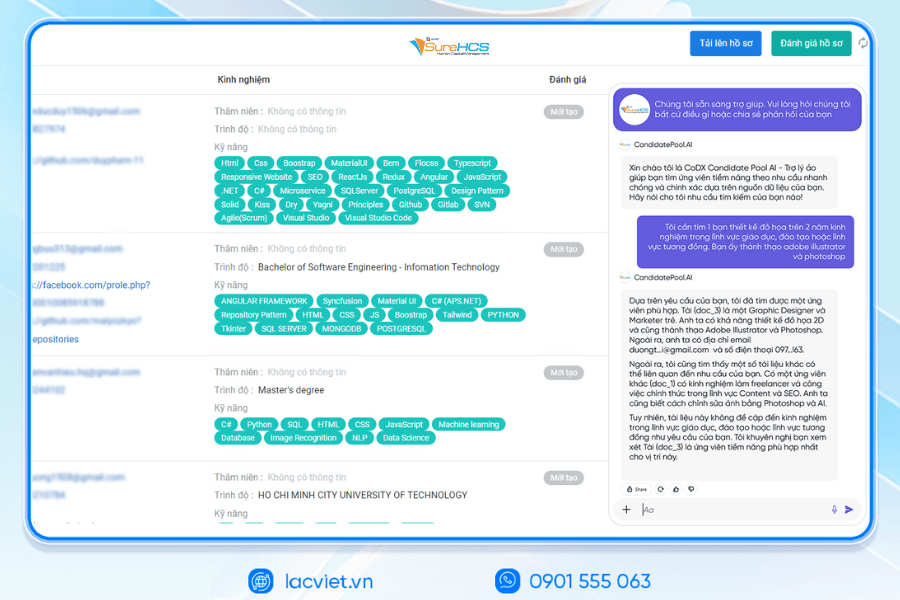
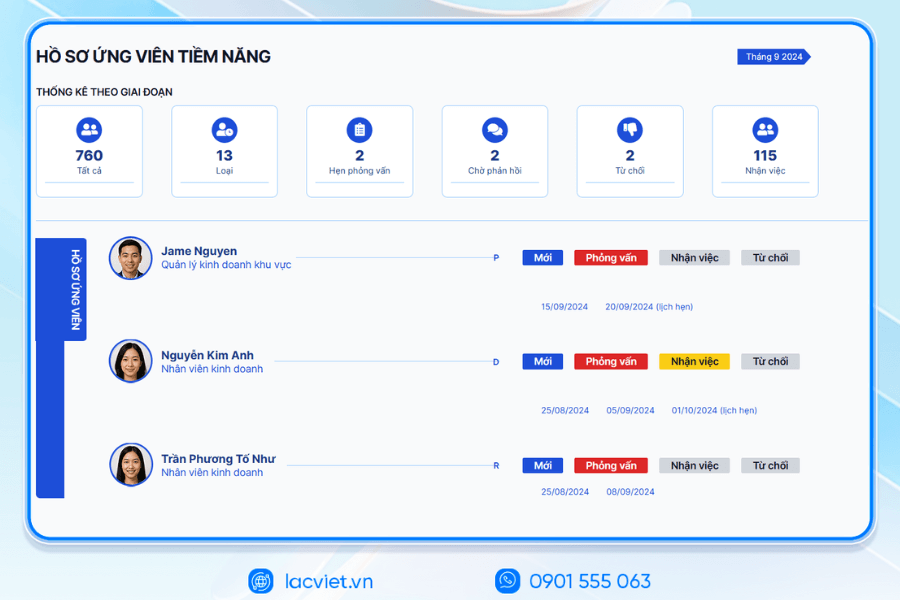
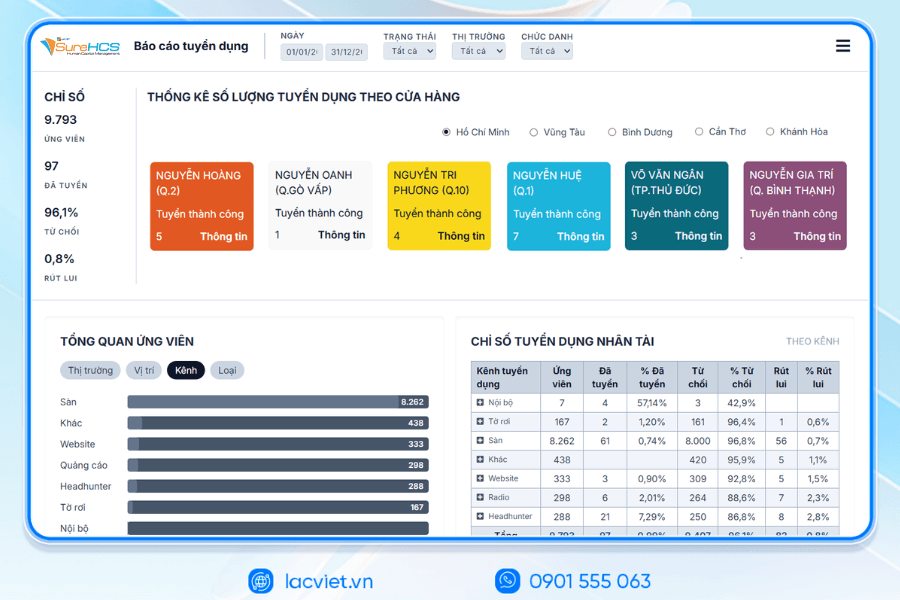
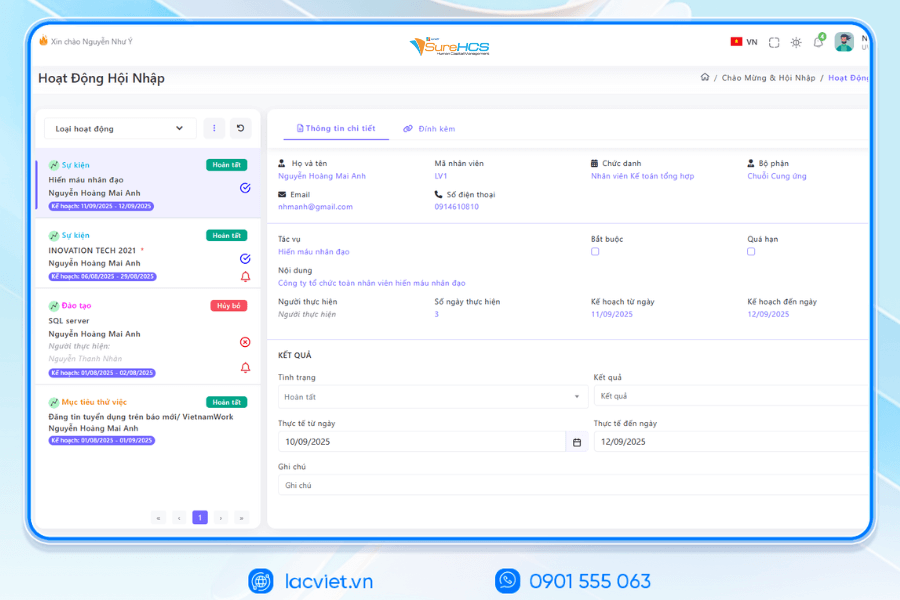
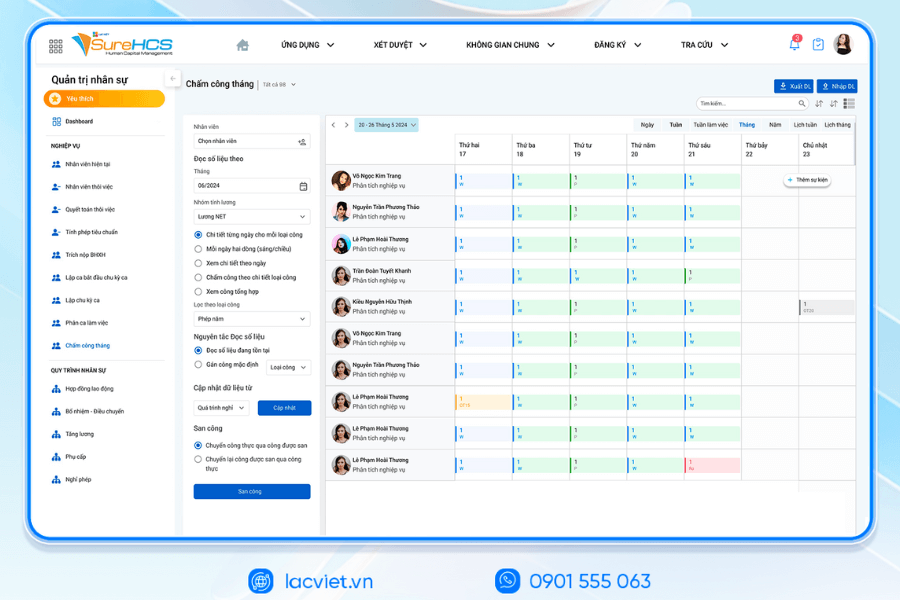
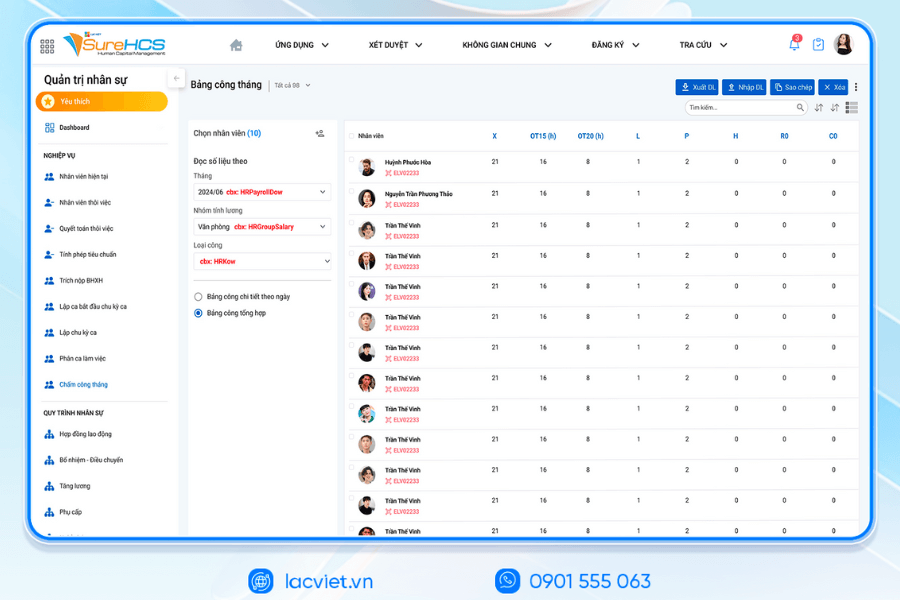
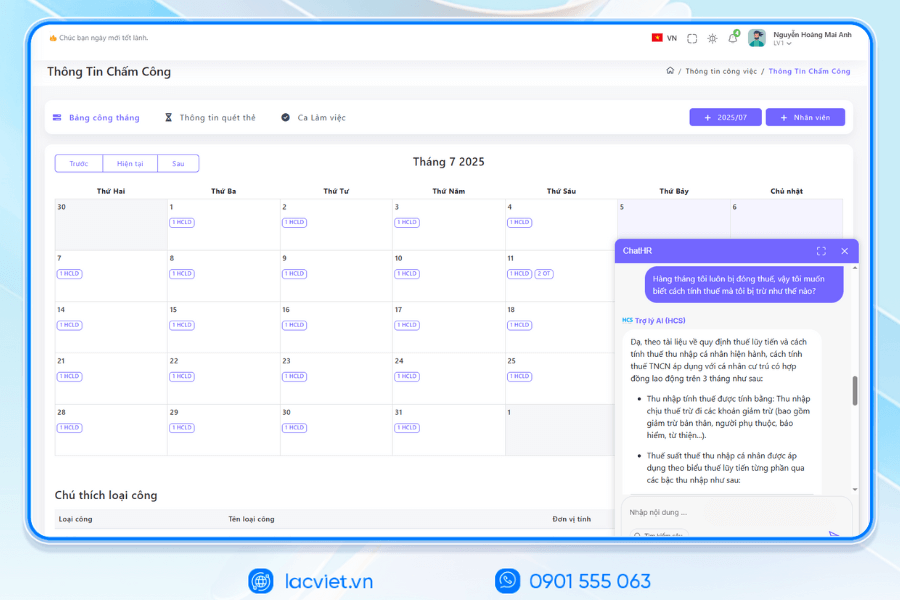
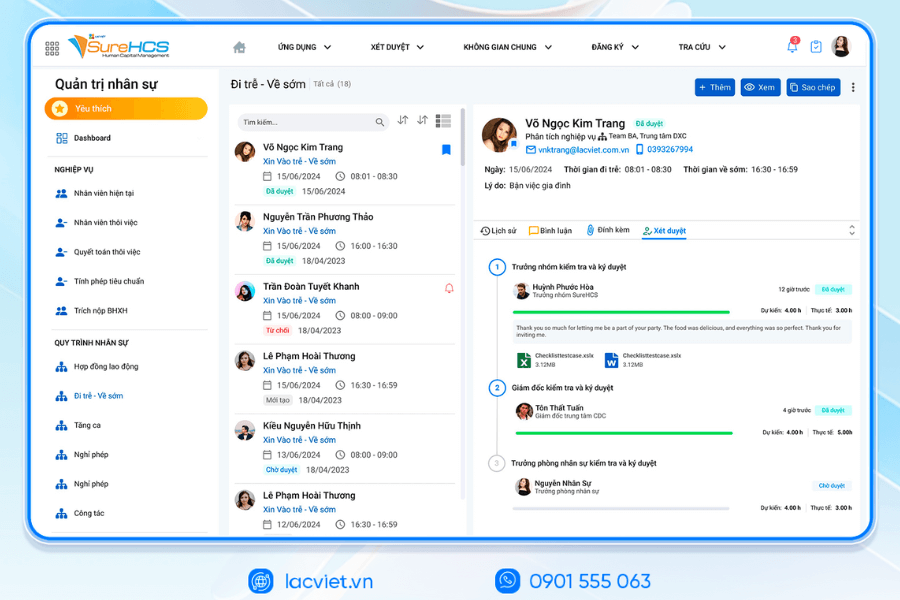
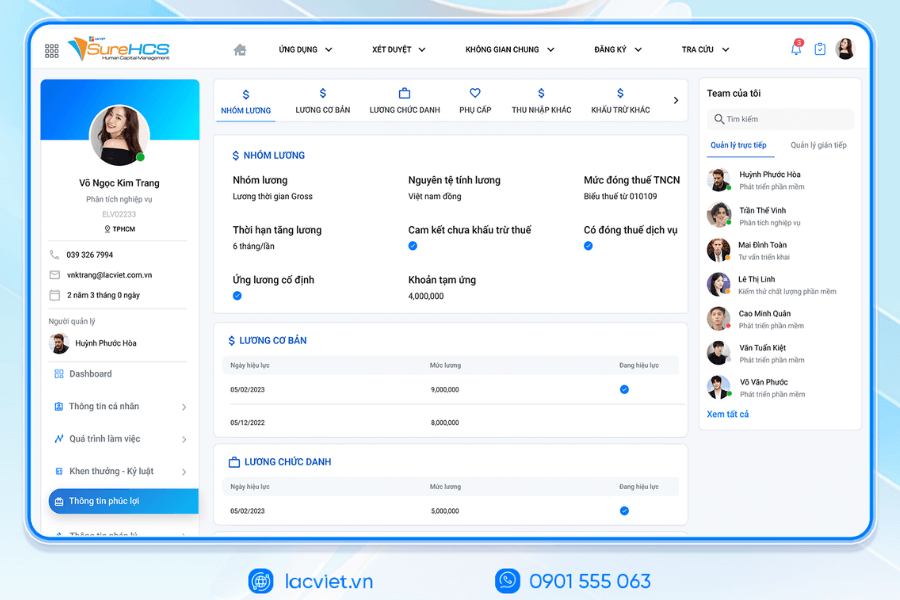
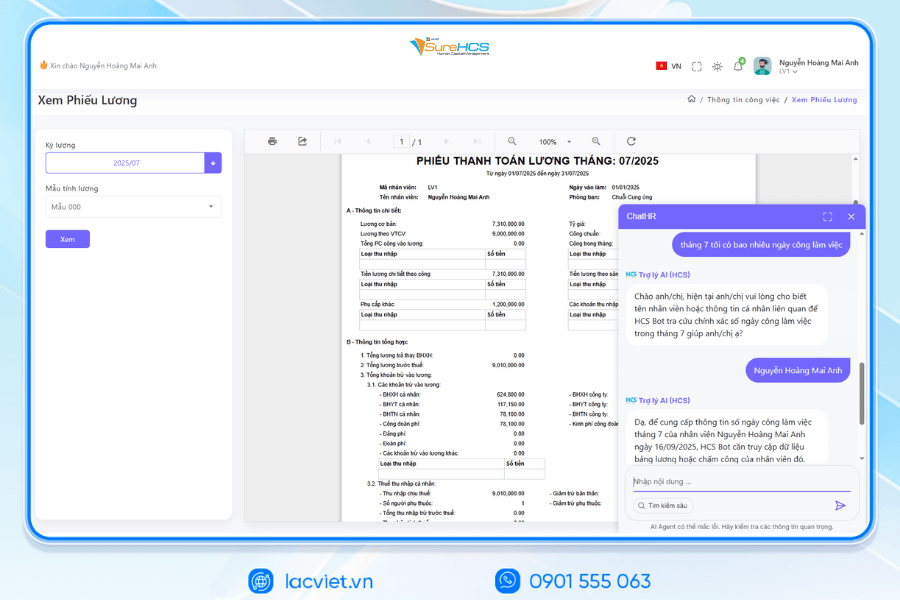
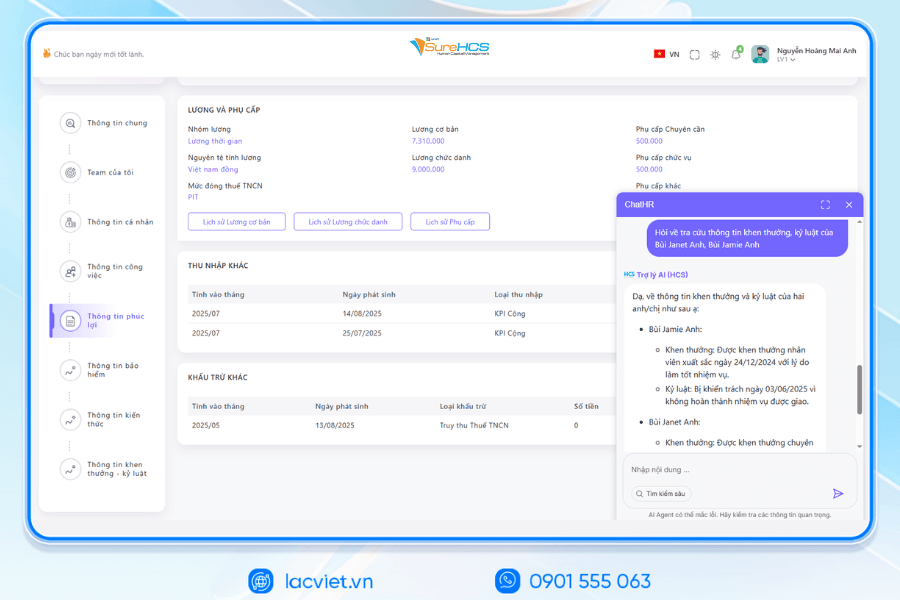
Lac Viet SureHCS HRM is the management solution, hr comprehensive help businesses automate the process of timekeeping, payroll management, benefits, and ensure compliance with the law on labour and SOCIAL insurance. Management software, human resources of Lac Viet is designed specifically to meet the needs of the organization medium and large volume of data, personnel, many, requires high accuracy.
With SureHCS HRM, businesses can:
- Track management allowances, bonus, pension in a transparent manner, including the terms do not get to not pay personal income tax.
- Tự động tính lương chính xác theo nhiều cơ chế khác nhau (lương cơ bản, lương 3P, hình thức trả lương theo sản phẩm), giảm thiểu sai sót tiết kiệm thời gian.
- Management process timesheets and absent effective support, performance evaluations, reward and punishment in a timely manner.
- Constantly updated regulations, the latest legislation on SOCIAL insurance, personal income tax, to help businesses comply with policies without losing the track craft.
WHY BUSINESSES SHOULD CHOOSE TOUCH THE SUREHCS?
- Customized according to the actual business, no pressure mold as packaged software.
- Handle the personnel – salaries complex that many software HRM other does not respond.
- Deep understanding operated business English & FDI, ensure compliance with legal Vietnam (labour, SOCIAL insurance and personal income tax).
- Ecosystem integration strength: attendance – payroll – bank – SI – electronic contract.
See details, feature & get FREE Demo
CONTACT INFORMATION
- Hotline/Zalo: 0901 555 063
- Email: surehcs@lacviet.com.vn
- Website: https://lacviet.vn | www.surehcs.com
- Office address: 23 Nguyen Thi Huynh, Phu Nhuan, ho chi minh CITY.CITY
Mastering the kinds of allowances not SOCIAL helps businesses manage personnel costs efficiently, and ensure legal rights for employees. Properly apply the allowances prescribed not only saves the cost of SOCIAL insurance contribution but also enhance the work experience, motivation, and increase employee engagement with business.
To deploy effective, the business should build a regulation salary transparency, store stock from full-constant updates of new legal provisions most. At the same time, the application software personnel management automation such as Vietnam SureHCS HRM will help to track, calculate, manage allowances correctly, reduce errors and save time.